
Blogs
Worldwide Tax & Revenue Collection Software Market: Why 12.04% CAGR Changes Everything
By pmarketresearch, 2026-09-18
Navigating the Global Tax & Revenue Collection Software Landscape: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
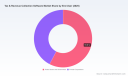
The worldwide tax and revenue collection software market has entered a period of sustained expansion, driven by the universal imperative to modernize financial infrastructure and ensure compliance across increasingly complex jurisdictions. Over the past five years, the sector has consistently outpaced broader enterprise software growth rates, with total market value projected to climb from approximately $11.45 billion in 2020 to nearly $43.57 billion by 2032. This trajectory reflects a compound annual growth rate exceeding twelve percent, signaling a structural shift rather than a cyclical surge. Governments and corporations alike are shedding legacy manual processes, replacing them with automated, data-rich platforms that can handle assessment, billing, collection, and reporting at scale. The market has reached a level of maturity where scale adoption is giving way to intelligent optimization, yet the pace of change remains brisk enough to reward organizations that act decisively and penalize those that delay modernization.
Despite the robust growth trajectory, the industry is navigating several critical inflection points that will shape competitive outcomes over the next decade. First, regulatory fragmentation continues to outpace standardization efforts. Tax authorities across different regions are implementing divergent digital reporting mandates, real-time filing requirements, and cross-border data sharing protocols. Software providers must reconcile these conflicting demands while maintaining system interoperability, which creates substantial architectural complexity and raises the barrier to entry for smaller vendors. Second, the migration from on-premise deployments to cloud-based environments is accelerating, but the transition is uneven. While cloud architectures deliver scalability, faster updates, and lower upfront capital expenditure, they also introduce new dependencies around data sovereignty, continuous subscription pricing, and vendor lock-in. Organizations with deeply embedded legacy systems face costly refactoring efforts, while newer adopters must navigate a crowded landscape of cloud-native solutions that vary widely in compliance depth and integration readiness. Third, talent scarcity is compressing margins and slowing product roadmaps. The demand for engineers and compliance specialists who understand both tax law and modern software architecture has pushed compensation benchmarks higher, particularly in North America and Western Europe. This labor constraints means that vendors must balance feature velocity with system stability, and buyers must evaluate whether prospective platforms can sustain long-term support without excessive customization.
PW Consulting
For executives evaluating this space, the immediate implication is clear: market growth does not automatically translate into frictionless adoption. Success will depend on selecting platforms that can absorb regulatory volatility, integrate cleanly with existing financial ecosystems, and scale without imposing unsustainable total cost of ownership. The organizations that treat tax and revenue software as a strategic capability rather than a compliance utility will be better positioned to convert regulatory pressure into operational advantage.
Key Drivers Shaping Market Trajectory
Several interconnected forces are accelerating investment in tax and revenue collection software, and each one reinforces the others. The first and most visible driver is technological innovation, particularly the infusion of automation and machine learning into compliance workflows. Modern platforms are moving beyond static calculation engines to dynamic systems that continuously ingest regulatory updates, validate transactional data, and flag anomalies before they become filing errors. Cloud-native architectures have enabled vendors to deploy updates rapidly, while APIs and prebuilt connectors have reduced the integration burden for enterprise resource planning systems, e-commerce platforms, and government legacy databases. The practical effect is a measurable reduction in manual reconciliation, faster remittance cycles, and improved audit readiness. Companies that once treated tax determination as a periodic administrative task now embed it into real-time transaction flows, which in turn creates richer data feedback loops for forecasting and revenue optimization.
The second driver is a shifting policy and regulatory environment that is effectively mandating digital transformation. Tax authorities are increasingly using technology not just to collect revenue, but to enforce transparency and reduce leakage. New rules requiring electronic filing for the overwhelming majority of business returns, combined with cross-border initiatives that push toward real-time digital reporting, are shrinking the window for manual intervention. These mandates are not abstract compliance exercises; they reshape procurement priorities. Public sector agencies and private corporations are investing in platforms that can automatically adapt to regulation changes, maintain jurisdictional tax calendars, and produce auditable records without bespoke configuration. As authorities tighten reporting frequency and data granularity, software that cannot keep pace becomes a liability rather than an asset.
The third driver stems from demand-side behavior, where both enterprises and government entities are demanding better visibility and faster collection cycles. Private corporations operating across multiple jurisdictions face mounting pressure to manage indirect tax exposure, reconcile cross-border transactions, and maintain consistent reporting standards. At the same time, public sector organizations are under political and fiscal pressure to modernize revenue collection, reduce delinquencies, and improve citizen experience. This dual demand is expanding the addressable market beyond traditional compliance functions into broader revenue cycle management, where assessment, billing, collections, and customer-facing portals are increasingly treated as a unified workflow. Organizations are no longer willing to accept fragmented tools that force staff to shuttle data between systems; they want end-to-end platforms that reduce cycle times and improve cash flow predictability.
The fourth driver involves cost structure and infrastructure economics. While cloud adoption generally lowers upfront capital requirements, operational expenses are not static. Hosting workloads for tax software, particularly those that require high availability and strict data residency, can face periodic pricing adjustments and scaling friction. At the same time, the specialized labor required to build and maintain these systems commands premium compensation, which influences both vendor pricing strategies and buyer total cost of ownership calculations. The net result is that organizations are evaluating platforms not only on functional breadth, but also on deployment efficiency, integration simplicity, and long-term operational economics. Solutions that minimize custom development, reduce ongoing maintenance overhead, and automate compliance updates are gaining preference over heavily customized legacy implementations. Together, these drivers are creating a market where adaptability, automation, and total lifecycle cost are becoming the decisive selection criteria.
Competitive Landscape and Leading Strategies
The competitive environment in tax and revenue collection software is defined by a mix of specialized compliance vendors, large enterprise platform providers, and public-sector system integrators. The market remains moderately concentrated, with the top three players holding a meaningful share and the top five collectively representing a majority of revenue. This concentration indicates that scale, brand trust, and deep compliance expertise still matter, but it also leaves room for differentiated positioning and targeted expansion. Leading organizations are not competing solely on feature count; they are competing on jurisdictional coverage, integration depth, deployment flexibility, and the ability to reduce the operational burden of compliance.
Tax Software Market
Specialized vendors have carved out strong positions by focusing on workflow precision and regulatory responsiveness. Some have built platforms around municipal and local government revenue management, combining assessment, billing, and collection modules into integrated suites that reduce fragmentation for public agencies. Others emphasize automated tax determination and global compliance, offering suites that support filing, remittance, and revenue recovery across multiple jurisdictions. A third group concentrates on real-time calculation and returns processing, embedding tax logic directly into transaction systems so that businesses can maintain consistency across sales channels. These specialists tend to differentiate throughdepth of compliance logic, speed of regulatory updates, and targeted sector expertise. Their strategic advantage lies in being able to absorb regulatory complexity on behalf of customers, which is particularly valuable for organizations operating across multiple tax regimes or managing high transaction volumes.
Larger enterprise and platform vendors bring a different set of strengths. Some provide cloud-based tax reporting and withholding automation designed for government revenue systems and large corporate environments. Others integrate tax compliance and reporting into broader public-sector ERP ecosystems, allowing agencies to manage revenue collection within a unified operational backbone. A few offer comprehensive corporate tax management suites that span determination, e-filing, and reporting, helping multinational organizations standardize processes across regions. The platform vendors typically compete on ecosystem breadth, enterprise scalability, and the ability to connect tax workflows with finance, procurement, and operational systems. Their challenge is balancing generalization with the jurisdictional nuance that compliance demands, which often leads them to partner with specialized content providers or to invest heavily in regulatory data maintenance.
Recent product and partnership activity illustrates how these players are sharpening their positions. One leading government-focused vendor enhanced its cloud-based property tax assessment and collection capabilities, reflecting a push to modernize public sector revenue workflows with more responsive, cloud-native tools. Another specialist introduced a solution aimed at tax due diligence and revenue recovery in transaction contexts, signaling an expansion beyond routine compliance into value-protection services for complex business events. A well-known calculation and compliance provider announced an integration with a major e-commerce platform to automate cross-border tax collection, highlighting the growing importance of embedded compliance in digital retail and marketplace environments. These moves show a broader pattern: vendors are extending their core capabilities into adjacent workflows, deepening cloud delivery, and forming integration partnerships that reduce friction for end users.
The market is also being shaped by regulatory and operational context that influences competitive strategy. Upcoming digital reporting mandates in major economic regions are pushing vendors to invest in real-time data exchange and continuous compliance monitoring. Simultaneously, stricter electronic filing expectations are raising the baseline for system readiness, while data privacy obligations require processors to maintain rapid incident response capabilities. Hosting economics and specialized labor costs add another layer of strategic consideration, encouraging both vendors and buyers to favor architectures that reduce custom maintenance and streamline updates. As a result, the competitive landscape is evolving along two complementary paths: consolidation among vendors that can deliver broad jurisdictional coverage and enterprise-grade reliability, and continued differentiation by specialists that offer deep workflow precision, faster regulatory adaptation, and sector-specific functionality. New entrants are most likely to succeed by targeting underserved jurisdictions, niche transaction types, or specific deployment models rather than attempting to compete head-on across the full compliance spectrum.
Debt Collection Software Market
Forward-Looking Trends and Commercial Implications
Looking ahead three to five years, the market is likely to be shaped by a small number of high-impact trends that will create clear commercial opportunities for prepared organizations. The first trend is the shift from periodic compliance processing to continuous, event-driven revenue management. As authorities demand faster reporting and transaction-level visibility, software will increasingly function as a real-time control layer rather than a back-office filing tool. This creates opportunities for vendors and buyers alike: vendors can expand into revenue optimization, delinquency management, and predictive cash flow features, while buyers can use continuous data flows to improve forecasting, reduce collection lag, and strengthen audit defensibility. Organizations that treat revenue collection as a continuous process will be better equipped to manage volatility and respond to regulatory changes without disruptive system rework.
A second trend is the growing importance of ecosystem integration and interoperable data standards. Tax and revenue software will be judged not only on what it does in isolation, but on how cleanly it connects with ERP platforms, e-commerce systems, payment processors, and government portals. The companies that invest in open APIs, standardized data models, and prebuilt connectors will reduce implementation timelines and lower the long-term cost of change. For buyers, this means prioritizing platforms that can slot into existing architectures without heavy customization. For vendors, it means that partnership strategy and integration breadth will become as important as core compliance logic. The commercial upside is substantial for players that can reduce integration friction, because slower, more expensive deployments remain one of the biggest obstacles to adoption in both public and private sectors.
The third trend is the steady expansion of cloud-based delivery combined with rising attention to data governance, sovereignty, and operational resilience. Cloud architectures will continue to dominate new deployments because they support faster innovation cycles and lower initial capital barriers, but buyers will increasingly scrutinize hosting models, data residency options, and incident response capabilities. This creates an opportunity for providers that can offer transparent governance controls, predictable scaling economics, and reliable update mechanisms. It also introduces risk: pricing volatility in cloud infrastructure, evolving privacy expectations, and regulatory divergence can undermine total cost assumptions if not managed proactively. Organizations that align their deployment strategy with clear data governance requirements and build flexibility into their vendor relationships will be better positioned to capture the benefits of cloud adoption without exposing themselves to avoidable operational surprises.
Strategic Recommendations for Decision-Makers
For executives and investors evaluating this market, the most important step is to align technology choices with the regulatory and operational trajectory rather than with short-term feature checklists. Public sector leaders and corporate procurement teams should prioritize platforms that demonstrate rapid regulatory update cycles, clean integration with existing financial systems, and deployment models that match their data governance requirements. Total cost of ownership should be assessed over a multi-year horizon, including integration effort, maintenance burden, and the cost of adapting to new reporting mandates. Organizations that standardize on adaptable, well-connected platforms will reduce future rework and improve their ability to absorb compliance changes without disrupting core operations.
For investors and strategic planners, the opportunity lies in identifying vendors and solution segments that combine jurisdictional depth with scalable delivery and strong integration positioning. Market growth will favor providers that can sustain compliance accuracy at scale, expand into adjacent revenue cycle workflows, and reduce implementation friction through partnerships and standardized data exchange. Monitoring product announcements, partnership activity, and regulatory milestones will provide early signals about which players are gaining traction and which segments are likely to see intensified competition. The companies that can translate regulatory pressure into streamlined, automated revenue processes are likely to capture outsized value as adoption broadens beyond compliance into operational efficiency.
Across all audience types, timely and granular intelligence is essential for converting market momentum into effective decisions. Segment-level adoption patterns, regional regulatory timelines, deployment economics, and vendor-specific product roadmaps can materially change procurement timing, investment thesis, and risk assessment. For decision-makers who need detailed segmentation data, competitive benchmarks, and tailored scenario analysis to support internal planning, the full PW Consulting research report provides a deeper view of the market structure and the strategic choices most relevant to your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Tax & Revenue Collection Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Car Video Monitors Market: Why 7.45% CAGR Reshapes Growth Through 2032
By pmarketresearch, 2026-09-18
Worldwide Car Video Monitors Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
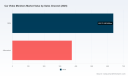
The global car video monitors market has entered a phase of sustained expansion, driven by the convergence of passenger entertainment expectations, advanced driver-assistance requirements, and vehicle electrification. From 2020 to 2025, revenue climbed from approximately USD 712 million to over USD 1,010 million, establishing a consistent upward trajectory that extends through the 2026–2032 forecast horizon. Compounding annual growth of roughly 7.45 percent positions the sector to approach USD 1,670 million by 2032. This growth is not merely linear; it reflects a structural shift in how vehicles are designed, sold, and experienced. Passengers increasingly view in-cabin video capabilities as standard amenities rather than premium add-ons, while manufacturers leverage displays to differentiate cabin experiences and support digital service ecosystems.
Despite the favorable macroeconomic and demand backdrop, the industry is navigating several inflection points. First, regulatory fragmentation around connected vehicle components is reshaping sourcing strategies. Recent guidance from the U.S. Department of Commerce targeting information and communications technology transactions involving certain foreign entities has introduced compliance complexity, prompting automakers and Tier-1 suppliers to reassess supply chain dependencies and certification pathways. This is particularly relevant for systems that combine video monitoring with connectivity, telematics, and cloud-linked entertainment services.
Second, material and component availability is tightening. Export controls on rare earth materials and associated processing equipment, alongside updates to critical minerals definitions that now include silicon used in semiconductor components for displays, are adding cost volatility and lead-time uncertainty. These dynamics affect both entry-level LCD/TFT panels and premium OLED modules, forcing designers to balance performance targets with supply resilience.
Driving Recorder (Car Dashcam) Market
Third, the market is split between integrated OEM deployments and aftermarket installations, each with distinct economics and risk profiles. OEM channels benefit from scale, brand alignment, and long validation cycles, while aftermarket channels offer faster time-to-market and greater flexibility in feature packaging. Navigating both channels requires distinct go-to-market models, pricing architectures, and partner ecosystems. The interplay between these channels, combined with regulation and material constraints, defines the current competitive environment and separates companies that can orchestrate cross-functional capabilities from those that remain siloed.
TV & Monitor Mounts Market
Key Demand and Supply Drivers
Technological innovation remains the most visible driver of market change. Display form factors have expanded beyond conventional rectangular panels to include round, foldable, rollable, and transparent designs, enabling manufacturers to integrate video monitors into headrests, roofs, dashboards, and consoles without compromising interior aesthetics. Advanced automotive displays now support higher brightness, wider viewing angles, and improved thermal management, which are prerequisites for rear seat entertainment (RSE) systems that must function under varied cabin conditions. In parallel, interactive and mixed-reality capabilities are emerging as differentiators. For example, recent demonstrations have showcased XR-aware rear seat interfaces powered by on-device computing, allowing passengers to engage with video content and ambient cockpit functions through more immersive, context-aware experiences. These advances are not cosmetic; they create new usage scenarios that increase perceived value and support premium pricing tiers.
Policy and regulatory environments are shaping both opportunities and constraints. Safety-oriented regulations continue to influence display placement, brightness limits, and distraction mitigation, especially for driver-facing and center-console interfaces. At the same time, connected-vehicle security rules are accelerating decisions about component provenance, software certification, and data handling. The net effect is a market where compliance capability has become a competitive asset. Suppliers that can document traceability, maintain approved sourcing lists, and navigate regional requirements are better positioned to secure long-term OEM contracts, while those with concentrated dependencies face higher scrutiny and potential delays.
Demand-side behavior is evolving across both consumer and enterprise segments. In premium and mid-tier passenger vehicles, rear seat video has transitioned from a luxury feature to a family and ride-hailing expectation, particularly in markets where long commutes and vehicle-based leisure time are common. Fleet operators and mobility service providers are also exploring cabin displays to enhance passenger experience, support route-based content, and enable service branding. This broad demand base is pulling product roadmaps toward modular architectures that can be configured by cabin size, vehicle segment, and channel. Pricing stratification reflects this diversity: entry-level panels in the 5–7 inch range typically occupy a lower price band, while premium OEM solutions above 10 inches with advanced features command substantially higher unit values. This spread encourages tiered product strategies and allows suppliers to address multiple vehicle classes without fragmenting their manufacturing footprint excessively.
Supply chain and cost structures are undergoing recalibration. The concentration of display panel manufacturing, semiconductor content, and specialty materials in a limited set of geographies has made end-to-end visibility a priority. Automakers and Tier-1s are diversifying sourcing, qualifying alternative materials where feasible, and negotiating longer-term agreements to stabilize costs amid evolving export controls and minerals definitions. At the same time, integration complexity is rising as video monitors become part of broader cockpit and infotainment platforms. Suppliers that combine display hardware, software interfaces, and system integration services reduce friction for OEMs, shorten validation cycles, and create stickier relationships. The cost equation increasingly favors partners who can deliver coordinated solutions rather than isolated components, especially as vehicles move toward domain-controlled architectures and centralized compute.
Competitive Landscape and Leading Strategies
The competitive field spans display specialists, Tier-1 system integrators, and infotainment-focused electronics manufacturers. Display leaders such as LG Display, Samsung Display, AU Optronics, and BOE Technology Group bring deep panel engineering capabilities, broad size ranges, and growing portfolios of automotive-grade OLED, microLED, and transformable form factors. Their strategies emphasize differentiation through form factor innovation, premium image quality, and cockpit-wide integration concepts. By offering rear seat entertainment options alongside cockpit displays, these companies position themselves as enablers of unified cabin experiences rather than isolated screen suppliers. Samsung Display has highlighted rooftop and round OLED configurations designed for immersive passenger entertainment, while AU Optronics has advanced interactive cockpit concepts that blend rear seat video with mixed-reality interactions. BOE’s wide span of automotive display sizes supports flexible cabin packaging across vehicle segments. These approaches reflect a broader industry shift toward displays that serve both functional monitoring and experiential entertainment roles.
Tier-1 integrators including Continental AG, Denso Corporation, Bosch, Hyundai Mobis, Visteon Corporation, and Panasonic Corporation add system-level value by embedding video monitors within infotainment, instrument cluster, and connected cockpit architectures. Their differentiation lies in software integration, validation expertise, and the ability to align displays with vehicle electrical architectures and safety requirements. For OEMs, this reduces integration risk and accelerates program timing. Companies such as Visteon and Bosch emphasize connected interfaces and cabin-wide user experiences, while Denso and Continental focus on robust automotive-grade delivery and cross-domain compatibility. Hyundai Mobis leverages its position across global vehicle programs to scale integrated electronics and display solutions, including video monitor integration for entertainment and interface applications.
Aftermarket and audio-visual specialists such as Pioneer Corporation, Alpine Electronics, and Panasonic further broaden the market by serving both OEM and retrofit channels. Their strengths include consumer-facing brand recognition, configurable product lines, and faster iteration cycles for headrest and rear seat video monitors. This channel diversity gives automakers and fleets flexibility to address different price points and vehicle lifecycles, while also enabling faster adoption in segments where full OEM redesign cycles are not feasible.
Recent developments illustrate how strategies are converging around experience-led differentiation. AU Optronics demonstrated an XR interactive window feature for rear seats, using on-device computing to support interactive video and mixed reality within smart cockpit concepts. Samsung Display later showcased new RSE options, including a compact round display and a larger rooftop OLED configuration, signaling a push toward immersive, form-factor-diverse passenger entertainment. These moves underscore a common theme: value is shifting from basic video output toward integrated, interactive cabin experiences that combine display hardware, compute, and software.
Market structure is evolving along multiple axes. Concentration remains moderate, with the top three firms capturing a meaningful share and the top five collectively representing the majority of revenue, which indicates room for differentiation but also a baseline of scale advantages. The landscape is simultaneously consolidating where integration and compliance capabilities matter most, and fragmenting where niche form factors, regional programs, and aftermarket flexibility create openings. New entrants and second-tier suppliers can gain traction by specializing in specific cabin zones, developing cost-optimized panels for volume segments, or offering rapid-turn aftermarket solutions. However, sustained leadership increasingly depends on the ability to manage regulatory complexity, secure material streams, and deliver coordinated hardware-plus-software offerings that align with OEM program timing and validation cycles.
Future Outlook and Strategic Trends
Over the next three to five years, the market is likely to be shaped by three interconnected trends. First, cabin video systems will increasingly function as part of broader digital cockpit platforms rather than standalone accessories. Displays in headrests, roofs, dashboards, and consoles will be coordinated through shared software layers, enabling consistent user experiences, unified content services, and more efficient hardware utilization. This creates opportunities for suppliers that can deliver end-to-end cockpit integration and for automakers that can leverage video monitors as anchors for in-vehicle services.
Second, form-factor diversity and interactive capabilities will become more mainstream across segments. Round, foldable, rollable, and transparent displays will move from showcase concepts toward selected production applications, especially in premium cabins and mobility services targeting passenger engagement. Mixed-reality and context-aware interfaces will expand where compute and content ecosystems support them, creating premium features that differentiate models and support higher unit values. Commercial opportunities will emerge for companies that can translate these capabilities into reliable, automotive-grade products with clear cost and validation pathways.
Third, supply chain resilience and compliance readiness will increasingly determine winning positions. Ongoing export controls on specialty materials, evolving definitions of critical minerals, and connected-vehicle transaction rules will continue to influence sourcing decisions and program timelines. Suppliers that maintain diversified sourcing, clear traceability, and regional compliance competence will be better equipped to secure long-term contracts and reduce program risk. Potential uncertainties include further regulatory tightening, cost pressure from material constraints, and the risk that premium features remain confined to high-end segments if validation and pricing challenges persist. These forces will reward disciplined portfolio management and agile channel strategies.
Actionable Guidance for Decision-Makers
For display and component manufacturers, the priority is to align portfolios with cabin-wide integration trends while strengthening compliance and sourcing resilience. This means investing in modular architectures that can serve headrest, roof, dashboard, and console applications, and ensuring that hardware roadmaps account for regional regulations and material constraints. Partnerships that combine panel technology with software interfaces and system validation can shorten OEM adoption cycles and increase stickiness.
For investors, the most durable value creation is likely to come from companies that blend differentiated display technology with integration capability and channel flexibility. Exposure to premium RSE solutions, cockpit-platform providers, and suppliers with transparent compliance and sourcing practices offers a balanced risk-return profile. Monitoring product launches that expand interactive or immersive features, alongside supply-side developments affecting materials and semiconductors, can provide early signals of competitive shifts.
PW Consulting
For procurement and program leaders, building multi-source strategies and clear qualification pathways is essential. Balancing OEM and aftermarket channels, targeting tiered pricing structures that match vehicle segments, and validating suppliers on both technical and regulatory criteria will reduce exposure to disruption. Full-report data on segment sizing, regional dynamics, pricing bands, and company-level market positions can support more precise sourcing decisions and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Car Video Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Capsule Endoscope Attitude Controller Market: Why 10.45% CAGR Redefines 2032 Value
By pmarketresearch, 2026-09-18
Worldwide Capsule Endoscope Attitude Controller Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
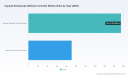
The global market for capsule endoscope attitude controllers has transitioned from a niche diagnostic adjunct to a structurally important category within gastrointestinal imaging. Historical data from 2020 through 2025 shows a consistent expansion trajectory, with cumulative revenue rising from approximately USD 175.4 million to USD 285.8 million. The forward-looking horizon through 2032 points to a sustained compounding path, reaching an estimated USD 573.1 million by the end of the forecast period and reflecting a compound annual growth rate of 10.45 percent. This scale of movement matters because it indicates that attitude control hardware—controllers, magnetic guidance units, robotic navigation interfaces, and related software—is becoming a commercial center of gravity rather than a peripheral accessory.
Two structural challenges define the current inflection point. First, the category is characterized by high market concentration. The top three players account for roughly 68.45 percent of total revenue, while the top five capture about 82.1 percent. Such concentration typically signals mature distribution channels, entrenched clinical relationships, and regulatory familiarity on the part of incumbents. At the same time, it compresses the strategic room for new entrants, especially in regions where reimbursement pathways and hospital procurement habits favor established vendors. For decision-makers, this means that raw clinical promise is insufficient; commercial traction requires alignment with purchasing committees, integration into existing diagnostic workflows, and demonstrable operational efficiency.
Second, the category is navigating a tension between technical capability and real-world adoption. External magnetic control systems and internal micro-robotic actuators represent different philosophies of how a capsule should be maneuvered inside the body. The former offers strong directional control at a system level, often with robotic or joystick interfaces, while the latter emphasizes miniaturization and in-capsule actuation. Neither approach has fully resolved the operational trade-off between control precision, procedure time, staff training burden, and cost per exam. In practice, this shows up as uneven uptake across institutions, with some early-adopter centers integrating active control into routine pathways and others treating it as a specialized tool for difficult cases. The challenge for leadership is to avoid overgeneralizing early success and instead evaluate where controlled navigation genuinely changes clinical throughput, diagnostic yield, or patient experience.
A third, subtler challenge is the regulatory and reimbursement environment. Certain systems have earned clearances or approvals for specific indications and patient populations, yet coverage policies have not always evolved in lockstep. As a result, even technically capable platforms can face uncertainty when hospitals attempt to scale usage beyond initial pilot programs. The implication is that commercial success depends as much on evidence generation, coding clarity, and procurement framing as on device sophistication. Organizations entering or expanding in this space need to plan for a prolonged validation cycle, not just a product launch milestone.
Key Drivers Reshaping the Market
The first and most visible driver is technological innovation that broadens what a capsule can do under active control. The category is moving beyond simple passive transit to systems that can adjust orientation, position, and viewing angles in real time. This shift matters because visualization quality and procedural flexibility are increasingly tied to how well a clinician can direct the capsule through complex anatomy. Recent product activity illustrates this trend: a magnetically controlled capsule system has expanded its commercial footprint by introducing a small bowel platform built around aspherical lens technology intended to widen the field of view and reduce distortion. Alongside that, the same platform has progressed through regulatory clearances and indication expansions that make it usable across broader age ranges and body types, including updated access for pediatric and higher-BMI populations in certain systems. These moves are not isolated hardware upgrades; they signal a deliberate attempt to make active control clinically practical across more patients and more gastrointestinal segments.
A second driver is the evolving regulatory and reimbursement landscape, which is becoming both an enabler and a gating factor. Some magnetically controlled systems have established regulatory status for active locomotion in gastrointestinal diagnostics, while others have secured approvals for stomach visualization or small bowel use with successive indication expansions. This staggered approval pattern shapes adoption because hospitals tend to prioritize platforms with clear regulatory standing and the strongest documentation for the procedures they perform most often. At the same time, reimbursement realities differ across settings. In some healthcare systems, standard wireless capsule endoscopy already has an established coverage framework for small bowel visualization, while advanced magnetic control options may still be treated as investigational for certain upper abdominal indications. The commercial implication is that vendors and adopters alike must treat evidence generation and policy engagement as integral to product strategy, not as after-the-fact activities.
The third driver is demand-side change, especially the growing pressure on healthcare providers to improve diagnostic efficiency while limiting invasive procedures. Capsule endoscopy already offers a less invasive alternative for many patients, but attitude control adds a more compelling value proposition: the ability to steer, pause, and reorient imaging in targeted regions rather than relying entirely on chance transit. For hospitals and imaging centers, this can translate into better coverage of suspicious areas, more consistent procedure quality, and potentially fewer repeat studies. For patients, the appeal may include reduced discomfort and greater confidence that the examination is being actively guided. Demand is therefore being shaped not only by clinical performance, but also by operational goals such as throughput, staff utilization, and procedural predictability.
Worldwide Ultra HD Endoscope Market
The fourth driver involves supply chain and cost structure dynamics. Active control platforms require a broader ecosystem than capsules alone: controllers, magnets, robotics, software, calibration support, maintenance, and training. This increases the importance of manufacturing consistency, component sourcing, service networks, and software reliability. In parallel, the market's concentration pattern suggests that incumbents are building durable relationships around service contracts, clinical training, and system integration. For competitors, this means that competing on capsule hardware alone is unlikely to be sufficient; differentiation is increasingly tied to total cost of ownership, workflow compatibility, and post-sale support. The market is gradually rewarding organizations that can reduce the friction of adoption across an entire institution rather than a single department.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive environment is dominated by companies that have pursued different positions along the control, indication, and market-access dimensions. One U.S.-headquartered firm with operations in China has emphasized a magnetically controlled capsule endoscopy system designed for precise translational and rotational control, particularly in stomach and gastrointestinal segments. Its recent activities show a blend of product progression and regulatory expansion: a small bowel system with aspherical lens technology was launched commercially, the small bowel platform received FDA clearance for expanded indications, and the stomach capsule indications were broadened to include younger patients and higher BMI ranges. This sequence reflects a strategy of extending a single control platform into multiple anatomical use cases while widening the addressable patient population. In practical terms, the company is positioning its technology not as a single-purpose tool, but as a shared navigation backbone that can support several examination types.
Another prominent player, based in Korea, has pursued a more compact control model with a hand-held magnetic controller for real-time navigation of its capsule in the esophagus, stomach, and duodenum. This approach highlights a different value proposition: the controller is designed to be intuitive and immediately usable, which can lower training barriers and make active control feel less like a specialized robotics project and more like an extension of existing endoscopic practice. The strategic message is that usability and direct clinician control can be as important as automation. For health systems that want magnetic control without a major operational overhaul, this type of design can be attractive because it reduces complexity and potentially accelerates adoption.
In China, multiple firms have advanced magnetically controlled systems that leverage either standing-type or robotic magnetic guidance. One Shenzhen-based company has moved forward with hospital deployment partnerships, including a strategic arrangement to introduce its magnetic controlled capsule endoscopy system at a major hospital. Another Chongqing-based group has developed capsule series with magnetically controlled variants and a fully automated magnetic control system for robotic attitude and navigation. These moves illustrate two parallel competitive themes: first, the importance of local distribution, clinical relationships, and institutional pilot programs in building credibility; and second, the growing divergence between systems that prioritize robotic automation and those that emphasize clinician-directed control. The Chinese market's scale and speed of adoption offer early evidence of how quickly magnetic control can move from niche trials into routine diagnostic pathways when supported by strong local partnerships.
Across these players, a few strategic patterns are emerging. First, the leaders are not competing solely on capsule optics or sensor quality; they are competing on control interfaces, procedural integration, and indication breadth. Second, regulatory milestones and clinical partnerships are being used as differentiators, especially where coverage policies and hospital procurement remain cautious. Third, the market is likely to see further consolidation pressure over time, not necessarily through mergers alone, but through adoption choices that favor platforms with wider indication coverage, established service networks, and clearer reimbursement positioning. At the same time, new entrants may still find room in specialty niches such as dedicated esophageal applications, pediatric use, or hybrid control solutions that blend clinician guidance with automated assistance. The overall landscape is therefore becoming less about a single winning architecture and more about the ability to match a control strategy to a defined clinical and commercial context.
Outlook for the Next Three to Five Years
Over the next three to five years, one likely trend is the continued widening of indications for active control platforms. As more systems gain clearances and as clinical experience accumulates, the market should move toward broader patient eligibility, more flexible use across gastrointestinal segments, and greater institutional comfort with magnetically guided procedures. This trajectory creates commercial opportunities for vendors that can document consistent performance across populations and settings, and for adopters that can standardize the technology into repeatable service lines rather than isolated pilot programs.
A second trend is the growing importance of workflow integration and automation balance. Hospitals are likely to favor systems that fit cleanly into scheduling, staffing, documentation, and data management processes. That does not mean every platform needs full automation; rather, it means the most successful offerings will probably be those that make clinician effort, training time, and reporting burden predictable. Hybrid models that combine guided control with decision support, image triage, or reporting assistance may gain traction because they address both clinical control and operational efficiency. The commercial opportunity lies in reducing the hidden costs of adoption: staff retraining, procedure variability, and administrative complexity.
A third trend concerns market structure and geographic divergence. Concentration at the top of the market is likely to persist in the near term, especially where incumbents have strong relationships, proven support infrastructure, and regulatory familiarity. However, regional dynamics will differ. In some markets, local champions with hospital partnerships and domestic approvals may strengthen their position quickly, while in others, global platforms may gain ground through broader indication coverage and international clinical evidence. The associated risk is that over-reliance on any single control paradigm or regulatory pathway could limit flexibility if reimbursement policies shift or if new evidence changes clinical preferences. Decision-makers should therefore treat geographic expansion and indication growth as interconnected, not independent, strategic choices.
Actionable Considerations for Decision-Makers
For manufacturers, the strategic priority is to define a control architecture that aligns with a clear clinical use case and then build the surrounding evidence, service, and integration model to support it. Competing on technical novelty alone leaves too much open to procurement scrutiny. It is more effective to target a well-defined patient population or procedure type, demonstrate measurable operational benefits, and prepare for the reimbursement and training requirements that determine whether a pilot can scale. Companies should also evaluate whether their platform is best positioned as a clinically focused tool, a workflow-integrated system, or an automation-enhanced solution, because each path implies a different go-to-market and support strategy.
Worldwide Robotic Scope Holder Market
For investors, the key question is how durable a company's differentiation will be once early regulatory and product milestones are achieved. Indications, hospital partnerships, and commercial launch activity are important, but they need to be evaluated alongside reimbursement positioning, concentration risk, and the cost of scaling service and training infrastructure. Preference should be given to businesses that show progress in converting clinical capability into repeatable revenue, not just product announcements. Geographic exposure is also worth scrutinizing, because market adoption can vary sharply depending on local approval status and purchasing practices.
For procurement and clinical strategy teams, the practical task is to assess attitude control not as a standalone device purchase, but as a change in diagnostic workflow. The right evaluation framework should consider procedure time, staff training requirements, intended patient populations, maintenance and service obligations, and the likelihood of reimbursement support for the targeted indications. Where possible, pilot programs should be designed to test operational fit and integration with existing reporting and data systems, rather than focusing solely on image quality. Detailed segmentation data on regional uptake, application mix, and type-level adoption patterns can help narrow these decisions, but the strategic value lies in connecting that information to institutional priorities and revenue models.
For organizations seeking a fuller picture of where the market is heading, deeper segmentation detail, competitive benchmarking, and indication-level context can clarify which opportunities are most realistic under current regulatory and reimbursement conditions. The commercial prize in this category is unlikely to go to the most ambitious technology in isolation; it will go to the players that can make active capsule control clinically credible, operationally manageable, and economically sustainable at scale.
For detailed analysis of this topic, please visit the official page: Worldwide Capsule Endoscope Attitude Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide 6-Tert-butyl-0-cresol Market: What the 4.45% CAGR Trajectory Really Means
By pmarketresearch, 2026-09-18
Navigating the Global 6-Tert-butyl-0-cresol Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
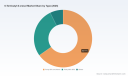
The global market for 6-Tert-butyl-0-cresol, widely recognized for its role as a high-performance antioxidant, has demonstrated consistent expansion over the past five years. Valued at approximately USD 275.5 million in 2020, the market reached USD 340.0 million by 2025. Projections indicate the market will expand to USD 462.69 million by 2032, growing at a Compound Annual Growth Rate (CAGR) of 4.45 percent throughout the forecast period from 2026 to 2032. This trajectory underscores the compound's entrenched position in industrial supply chains, particularly within polymer stabilization and fuel additive sectors. Revenue figures are primarily denominated in USD Million, reflecting the commodity-like nature of the chemical while highlighting significant margins available through specialization.
Despite this positive growth outlook, the industry stands at a critical juncture defined by three converging challenges. First, regulatory scrutiny regarding chemical safety has intensified, particularly regarding downstream applications in food packaging and consumer plastics. Compliance requirements such as EU REACH authorization for use above certain thresholds in plastics have created friction for manufacturers who previously relied on established legacy formulations. This regulatory pressure forces a reevaluation of supply chains and product specifications, potentially slowing adoption in sensitive regions while creating opportunities for certified, high-purity alternatives.
Second, supply chain volatility poses a significant risk to margin stability. Raw material inputs, specifically phenol feedstocks, have experienced price fluctuations due to geopolitical tensions and supply disruptions in key production hubs. For instance, recent data indicates an 8 percent rise in phenol feedstock prices in the first quarter of 2025 driven by these disruptions. Such volatility complicates cost forecasting for producers and can erode profitability if hedging strategies are not robust. Manufacturers must navigate these cost pressures without passing excessive burdens to downstream customers who are themselves facing economic headwinds.
Third, the market exhibits moderate concentration, with the top five players commanding a significant share of total revenue. This structure creates a barrier to entry for new competitors but also concentrates risk. Any production outage or strategic misalignment among key suppliers can ripple through the global supply network. Furthermore, trade policies, such as specific duty codes applied to imported chemical grades in major economies, add layers of complexity to international logistics and pricing strategies. Companies must balance local production advantages against the efficiency of globalized supply networks.
Key Drivers of Market Evolution
Several foundational factors are driving the momentum observed in the 6-Tert-butyl-0-cresol sector. Understanding these drivers is essential for stakeholders looking to capitalize on emerging opportunities or mitigate potential risks.
Technological Innovation and Material Performance
The primary engine of demand remains the critical need for material durability in high-performance applications. 6-Tert-butyl-0-cresol serves as a vital antioxidant, preventing degradation in polymers, rubbers, and petroleum products exposed to harsh environmental conditions. As industries push for longer-lasting materials to reduce waste and lifecycle costs, the specification for higher purity grades is becoming standard. The market segmentation reflects this shift, with the segment requiring purity levels of 99 percent and above representing the largest revenue share. This trend is not merely about meeting minimum standards but about enhancing performance efficiency in automotive plastics and industrial rubber components where failure is not an option.
Innovation is also extending beyond traditional rubber and plastic uses. There is growing interest in specialized grades tailored for specific polymer matrices where standard antioxidants may interfere with curing processes or color stability. Manufacturers who invest in refining purification technologies to deliver consistent high-purity outputs gain a competitive edge, allowing them to command premium pricing and secure long-term contracts with demanding original equipment manufacturers (OEMs).
Di-tert-Butyl Peroxide (DTBP) Market
Policy and Regulatory Environment
Regulatory frameworks are reshaping how 6-Tert-butyl-0-cresol is sourced, processed, and applied. In Europe, stricter authorization requirements under REACH for uses above 0.1 percent in plastics have forced producers to ensure comprehensive documentation and safety data. Similarly, restrictions on food contact applications in various jurisdictions require clear separation between industrial grades and those approved for consumer-facing products. This bifurcation creates a need for distinct production lines and rigorous quality control protocols.
Trade policies also influence market dynamics. For example, specific duty classifications in the United States apply differential rates to imported chemical grades depending on their country of origin and trade agreement status. These tariffs influence sourcing decisions, encouraging buyers to seek suppliers within free trade zones or local manufacturers to avoid cost penalties. Consequently, regulatory compliance is no longer just a legal requirement but a strategic lever that determines market access and cost structures.
Demand-Side Shifts in Manufacturing
Downstream demand is evolving as composite industries modernize. The automotive sector, a major consumer of polymer stabilizers, is shifting toward lightweight materials to improve fuel efficiency and support electrification. These new material formulations often require precise antioxidant protection to maintain structural integrity over extended lifecycles. Similarly, the construction and infrastructure sectors are increasingly utilizing synthetic rubbers and engineered plastics that rely on effective stabilization to withstand weathering and UV exposure. This demand for durability translates directly into sustained consumption of high-performance antioxidants.
Additionally, there is a growing emphasis on supply chain resilience among procurement teams. Following recent global disruptions, industrial buyers are prioritizing suppliers who can guarantee consistent availability over those who offer only the lowest spot prices. This shift benefits established manufacturers with robust production capacities and diversified supply chains, allowing them to build stronger partnerships with key accounts in the polymer and fuel additive sectors.
Supply Chain and Cost Structure Dynamics
The cost structure of 6-Tert-butyl-0-cresol production is closely tied to petrochemical feedstock availability and energy costs. Fluctuations in phenol prices, often driven by upstream capacity constraints in Asia-Pacific regions, directly impact production margins. Suppliers must manage these input costs carefully, often utilizing long-term feedstock contracts or vertical integration strategies to stabilize expenses. Energy intensity in the manufacturing process also means that regional energy prices and carbon regulations can affect the competitiveness of production facilities in different geographies.
Logistics and distribution networks further influence the cost landscape. Regions with established chemical infrastructure benefit from lower handling and transportation costs, while remote markets may face higher landed costs due to freight and storage requirements. Efficient supply chain management, including strategic inventory positioning, becomes a key differentiator for suppliers aiming to offer reliable delivery schedules despite global logistical complexities.
Competitive Landscape and Leading Strategies
The competitive environment for 6-Tert-butyl-0-cresol is characterized by a mix of global specialty chemical producers and regional manufacturers who have expanded their capabilities to meet international standards. The market concentration, indicated by a combined share of over 48 percent held by the top five entities, suggests a mature landscape where scale and expertise provide significant defensive moats.
PW Consulting
SI Group, headquartered in the USA, stands as a leading global producer, marketing the compound primarily as antioxidant BHT for plastics, rubber, and petroleum applications. Their strategic positioning relies on broad global reach and established brand recognition within the industrial additives community. By maintaining high production standards and diverse application support, they secure a strong foothold in North American and international markets where reliability is paramount.
In Asia, Songnox Antioxidants, part of the Songwon Industrial Group based in South Korea, supplies the compound as a high-performance antioxidant for polymer stabilization and industrial uses. Their approach emphasizes technical service and integration into broader polymer additive solutions. This allows them to capture value not just from the chemical itself but from the performance improvements they enable for downstream polymer processors.
Chinese manufacturers play a substantial role in the supply base, with companies like Beijing Tiangang Auxiliary, Zhejiang Friends Chemical, and Chihon Industry actively producing grades for antioxidants in plastics, synthetic rubber, food packaging, and rubber processing. Beijing Tiangang Auxiliary focuses on antioxidants for plastics and synthetic rubber, including food packaging applications where regulatory compliance is critical. Zhejiang Friends Chemical produces pharmaceutical and industrial grades, catering to sectors that require exceptional purity and documentation. Chihon Industry serves the rubber processing and polymer additives market, leveraging regional manufacturing efficiencies to compete on cost and availability.
The market is evolving through both consolidation and specialization. Larger players are likely to pursue strategic acquisitions or partnerships to secure feedstock supply chains and expand geographic coverage. Meanwhile, smaller or regional producers may differentiate by focusing on niche purity specifications or localized service capabilities. The barrier to entry remains high due to the technical knowledge required for consistent high-purity production and the capital intensity of the manufacturing process. New entrants must navigate not only production challenges but also the complex web of trade duties and regulatory authorizations that govern cross-border chemical trade. Differentiation strategies increasingly revolve around the ability to provide certified, traceable supply chains that meet the stringent requirements of regulated industries.
O-Cresol (CAS 95-48-7) Market
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, several trends will define the trajectory of the 6-Tert-butyl-0-cresol market. Stakeholders should anticipate shifts in demand patterns, regulatory frameworks, and competitive dynamics that will create both risks and opportunities.
First, the demand for high-purity grades is expected to outpace the general market growth rate. As polymers and composites are used in more demanding environments, such as electric vehicle components and advanced construction materials, the tolerance for impurities decreases. This trend favors producers with advanced purification capabilities and robust quality assurance systems. Companies that can reliably supply 99 percent purity and above will likely capture greater value share, while commodity-grade segments may face margin compression due to competition and substitution risks.
Second, regulatory divergence between regions will create a multi-tiered market structure. While some regions tighten restrictions on specific applications, others may maintain more permissive standards for industrial uses. Manufacturers with the flexibility to adjust formulations and documentation for different regional requirements will gain a strategic advantage. This could lead to a scenario where supply chains are segmented by compliance level, with premium, fully certified streams serving sensitive markets and standard streams serving industrial applications with less restrictive oversight.
Third, supply chain localization and regionalization trends may accelerate. Trade policies, including duties on imports from non-free trade agreement countries, combined with the desire for supply security, may encourage buyers to source closer to end markets. This presents an opportunity for regional producers to expand their footprint and capture demand that previously flowed through global logistics networks. However, it also requires investment in local production capacity and compliance infrastructure to meet regional standards.
Potential risks include further tightening of chemical safety regulations that could restrict certain application areas, particularly those involving consumer contact. Additionally, volatility in raw material costs could remain a persistent challenge, requiring agile procurement and pricing strategies. Companies must remain vigilant about geopolitical developments that could disrupt feedstock supply or alter trade dynamics, as these factors can quickly change the competitive calculus.
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be investing in purification technologies and certification capabilities to access high-value segments. Aligning production processes with evolving regulatory requirements, such as REACH authorization and food contact restrictions, will protect market access and enable premium positioning. Strengthening supply chain resilience through diversified feedstock sourcing and strategic inventory management will also mitigate cost volatility risks.
Investors should focus on companies with proven high-purity production capabilities and strong compliance frameworks. Evaluating exposure to regulatory risks and the ability to navigate trade policies will be critical in assessing long-term value. Opportunities may exist in consolidation plays where scale and geographic diversification can drive efficiency and market share gains in a growing market.
Procurement and supply chain leaders should prioritize supplier partnerships based on reliability and compliance assurance rather than price alone. Diversifying the supplier base to include both global and regional sources can reduce vulnerability to disruptions and trade barriers. Engaging early with suppliers to understand their capacity for meeting future purity and regulatory requirements will ensure continuity of supply for critical applications.
For stakeholders seeking detailed segmentation data, regional breakdowns, and customized strategic scenarios, comprehensive industry research reports provide the granular intelligence needed to refine these strategies. Deep-dive analysis into production capacity, capacity utilization, and specific regional demand drivers can further validate investment theses and operational plans.
For detailed analysis of this topic, please visit the official page: Worldwide 6-Tert-butyl-0-cresol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Airport Furniture Market: Why the 5.45% CAGR Story Unfolds Beyond Growth
By pmarketresearch, 2026-09-18
Navigating the Worldwide Airport Furniture Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global airport furniture market has demonstrated remarkable resilience and steady expansion over the past half-decade. Valued at approximately $3.15 billion in 2020, the market has grown consistently to reach an estimated $4.45 billion by 2025. This trajectory reflects a compound annual growth rate of 5.45 percent across the 2026-2032 forecast horizon, with projected revenues climbing toward $6.45 billion by 2032. Such sustained expansion underscores the sector's fundamental role in supporting modern aviation infrastructure and passenger experience standards.
This growth is not merely cyclical but structural, driven by long-term investments in terminal redevelopment, capacity expansion at major hubs, and the modernization of aging facilities in emerging markets. However, the path forward is not without friction. Several critical challenges are reshaping how manufacturers, suppliers, and airport operators approach furniture procurement and design. First, the intensifying focus on sustainability and green building certifications is forcing a fundamental reevaluation of material selection, manufacturing processes, and end-of-life considerations. Airports are increasingly mandated to meet stringent environmental standards, which complicates traditional procurement models that historically prioritized cost and durability over ecological impact.
Second, supply chain volatility and regulatory shifts around material sourcing are introducing new cost structures and lead time uncertainties. Recent trade policy adjustments, including tariff measures on certain upholstered and wood-based products in key markets, have altered the competitive calculus for imported furniture and pushed stakeholders to reconsider sourcing strategies. These regulatory dynamics are not static, and their prolonged uncertainty complicates long-term planning for both manufacturers and airport procurement teams. Third, the rapid evolution of passenger expectations is raising the bar for functionality and integration. Travelers now expect seamless access to power, connectivity, and flexible seating configurations that adapt to varying dwell times and crowd densities. Furniture that fails to accommodate these demands risks becoming a liability rather than a value driver in terminal design.
Together, these challenges represent a pivotal moment for the industry. Companies that continue to treat airport furniture as a purely commodity-driven category will likely find themselves squeezed by margin pressure, compliance costs, and shifting buyer preferences. Conversely, those that proactively align product development with sustainability mandates, regulatory realities, and passenger-centric design principles are positioned to capture disproportionate value as the market expands.
Key Drivers Shaping Market Dynamics
Technological Innovation and Passenger-Centric Design
The integration of technology into airport furniture has moved from a premium afterthought to a baseline expectation. High-density seating with embedded power solutions, modular configurations that adapt to fluctuating passenger flows, and integrated waste and recycling units are becoming standard specifications in new terminal builds and major renovations. The emphasis on flexibility is particularly pronounced. Airports operate in environments where passenger volumes fluctuate dramatically by hour, season, and route network changes. Furniture systems that can be reconfigured quickly without specialized labor or significant downtime offer clear operational advantages. Manufacturers that have invested in modular architectures, lightweight yet durable materials, and seamless integration of charging infrastructure are gaining favor in competitive bidding processes.
Regulatory and Sustainability Pressures
Environmental regulation and voluntary certification programs are reshaping procurement criteria across regions. Airports pursuing green building certifications are prioritizing furniture made from recycled content, sustainably sourced materials, and designs that facilitate disassembly and recycling at end-of-life. This shift is not purely ethical; it carries tangible financial implications through eligibility for incentives, alignment with operator sustainability targets, and improved public perception. At the same time, regulatory measures around material sourcing and imports are influencing cost structures. Recent tariff actions on certain upholstered furniture and wood-based products in the United States illustrate how trade policy can alter the economics of imported seating solutions. While some measures have been deferred, the underlying uncertainty encourages regional sourcing diversification and closer scrutiny of supply chain dependencies.
Airport Lighting Market
Demand-Side Shifts in Passenger Behavior and Airport Operations
Rising global air passenger volumes continue to drive demand for high-capacity, comfortable, and durable terminal furniture. Airports are not simply adding seats; they are rethinking how spaces function. Gate areas, security queues, landside arrivals, and premium lounges each present distinct usage patterns that require tailored solutions. The growing prevalence of longer layovers, expanded retail and dining footprints, and the blurring of boundaries between waiting and leisure spaces have elevated the importance of lounge and office furniture alongside traditional seating. Operators are also placing greater value on furniture that supports wayfinding, crowd management, and hygiene considerations, lessons reinforced by recent operational disruptions.
Supply Chain Evolution and Cost Structure Realignment
The post-pandemic period exposed significant vulnerabilities in global supply chains, prompting airports and manufacturers to reassess sourcing models. Lead time variability, logistics costs, and material availability have all influenced pricing dynamics. In response, many suppliers are expanding regional manufacturing footprints, investing in inventory buffering for core product lines, and developing stronger partnerships with airport operators to align production cycles with procurement timelines. These adjustments are gradually stabilizing supply but also reflect a broader trend toward resilience over pure cost minimization. For buyers, this means a shift in evaluation criteria that balances total cost of ownership, reliability, and compliance with operational schedules.
Competitive Landscape and Leading Strategies
The worldwide airport furniture market remains relatively fragmented at the top, with the largest three players accounting for less than a fifth of total revenue and the top five representing just over a quarter. This concentration suggests ample room for specialized leaders to differentiate through design, regional expertise, and integrated service offerings rather than relying purely on scale. Several manufacturers have established distinct strategic positions that illuminate the pathways to competitive advantage in this sector.
Hotel Furniture Market
Arconas has carved out a leading position in North America by emphasizing high-performance seating, power integration, and modular counter solutions that span the passenger journey from curb to gate. Its recent activity at major industry exhibitions, including the launch of new seating series designed for flexible passenger-centered spaces, signals a continued focus on adaptability and experience-driven design. AGATI, a family-owned U.S. manufacturer with deep roots in durable, custom terminal furniture, has reinforced its differentiation through thought leadership on emerging trends such as flexible layouts and high-density seating. Its emphasis on regional and international airport environments highlights the value of tailored solutions that balance durability with aesthetic coherence.
In Europe, Zoeftig leverages more than fifty years of experience to supply ergonomic chair systems and terminal furniture to a broad international airport base, with a clear focus on comfort, durability, and the ability to deliver both bespoke and off-the-shelf options. Kusch+Co, another design-driven European manufacturer, has built a substantial international footprint by prioritizing capacity, safety, and comfort across beam seating, waiting benches, and lounge soft seating. Vitra complements this landscape with a strong design orientation, offering extensive airport seating portfolios that emphasize high-quality public space design across waiting zones, gates, and lounges. Sellex adds further variety with design-oriented benches and chairs fabricated from aluminum and stainless steel, targeting both waiting and commercial terminal integration.
Beyond these established Western manufacturers, active players in Asia Pacific and China are expanding their global reach. UFL Airports provides end-to-end custom solutions for landside to airside environments with a notable presence in Asia Pacific, while Winner Furniture and Oshujian Furniture have built extensive project portfolios in public seating and airport chairs, exporting to multiple regions including the Middle East, Southeast Asia, and Europe. ModernLine Furniture and Harrows contribute specialized strengths in upholstered lounge, banquette, and soft seating solutions, reflecting the market's growing appetite for differentiated comfort and aesthetic variety.
The competitive evolution is characterized by both consolidation pressure and continued fragmentation at the specialist level. Larger players with broad geographic reach and integrated product lines are well positioned to serve multi-site airport groups and large-scale redevelopment programs. At the same time, niche manufacturers that excel in specific product categories, regional certifications, or customization capabilities retain strong value propositions for airports with unique design requirements or localized procurement preferences. Trade show activity and product launches in recent months illustrate a market where differentiation is increasingly tied to passenger experience, sustainability credentials, and the ability to deliver flexible, technology-ready configurations. New entrants and regional suppliers are likely to continue challenging incumbents in cost-sensitive segments, while established leaders defend their positions through design leadership, service integration, and long-term airport partnerships.
Future Trends and Strategic Outlook
Looking ahead to the next three to five years, several interconnected trends will define the market's direction and shape the commercial opportunities available to manufacturers, investors, and airport operators. The first is the accelerating convergence of sustainability and performance. Furniture that meets green building criteria while delivering high durability, low maintenance, and integrated functionality will increasingly become the default expectation rather than a premium option. Manufacturers that can substantiate environmental claims with transparent material sourcing, recyclable architectures, and lifecycle efficiency will gain a meaningful edge in procurement evaluations. This trend also creates opportunities for material innovation, including advanced composites, recycled metals, and responsibly sourced wood alternatives that satisfy both regulatory and aesthetic demands.
PW Consulting
The second trend is the deepening integration of passenger-facing technology into furniture systems. Seating with dependable power access, modular layouts that respond to real-time passenger flow, and designs that support digital wayfinding and connectivity will move further into the mainstream. Airports are under pressure to optimize dwell space utilization, improve passenger satisfaction scores, and accommodate diverse traveler profiles ranging from business commuters to long-haul transit passengers. Furniture that adapts to these needs without requiring extensive retrofitting will be particularly valuable in both new builds and phased terminal upgrades. This creates a clear commercial pathway for suppliers that can offer integrated solutions rather than standalone seating products.
The third trend involves the ongoing realignment of supply chains and regulatory landscapes. Trade policy uncertainty, evolving material standards, and shifting cost structures will continue to influence sourcing decisions. Airports and manufacturers alike are likely to pursue greater regional diversification, stronger inventory planning, and closer collaboration between design, production, and procurement teams. While this can introduce short-term complexity, it also rewards organizations that build flexible supply networks and maintain a clear view of regulatory developments across key markets. The commercial opportunity lies in anticipating these shifts early and positioning product portfolios to remain competitive under multiple regulatory and cost scenarios.
These trends are not without risk. Overinvestment in narrow technology features that fail to gain operational traction, misinterpretation of sustainability requirements, or exposure to sudden policy changes can erode margins and delay project wins. The most resilient players will be those that balance innovation with practical deployment, align product roadmaps with verifiable airport priorities, and maintain the agility to adapt as regulations and passenger expectations evolve.
Actionable Recommendations for Decision Makers
For manufacturers and product developers, the imperative is to embed sustainability, modularity, and technology integration into core product architectures rather than treating them as add-on features. Prioritize verifiable environmental credentials, design for disassembly and material recovery, and develop seating and lounge systems that can be reconfigured with minimal effort. Strengthening regional supply capabilities and maintaining close alignment with airport procurement cycles will reduce exposure to lead time volatility and tariff uncertainty. Differentiation through design quality, durability, and integrated power and connectivity solutions remains a proven path to commanding premium positioning in competitive bids.
For investors evaluating exposure to this sector, focus on companies with clear regional strengths, diversified product portfolios, and demonstrated ability to serve both large hub programs and specialized regional projects. Firms that combine design leadership with practical execution, possess transparent sustainability practices, and maintain flexible supply chains are better positioned to benefit from the projected growth trajectory. Monitor regulatory developments in key import markets and assess how potential policy shifts could affect cost structures and competitive dynamics across regions.
For airport procurement teams and operators, the priority is to align furniture specifications with long-term operational goals rather than short-term cost minimization. Evaluate total cost of ownership, including maintenance, reconfiguration flexibility, passenger experience impact, and compliance with sustainability targets. Engage suppliers early in the terminal planning process to ensure furniture strategies integrate seamlessly with spatial design, passenger flow management, and technology infrastructure. Building multi-phase procurement roadmaps with clear performance criteria will help balance budget constraints with the need for durable, future-ready terminal environments.
As market dynamics continue to evolve, the organizations that succeed will be those that treat airport furniture as a strategic component of the passenger experience and terminal operations, not a peripheral procurement item. Detailed segmentation data, region-specific cost structures, and tailored scenario planning can further sharpen these strategic decisions and uncover opportunities that broader market narratives may overlook. For decision makers seeking a deeper, data-backed view of the worldwide airport furniture market, the complete research report provides comprehensive breakdowns across regions, product types, materials, and competitive profiles, along with customized guidance aligned to specific business objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Airport Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How 5G Is Redefining Copper Clad Laminate Market Dynamics Through 2032
By pmarketresearch, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Worldwide Copper Clad Laminate for 5G Market
Market Dynamics: A Trajectory of Growth Amid Structural Pressures
The global market for copper clad laminate (CCL) tailored to 5G applications has firmly entered a phase of accelerated expansion. Valued at over 4.2 billion USD in 2025, the sector is projected to surpass 9.7 billion USD by 2032, reflecting a compound annual growth rate of 12.42 percent. This growth trajectory, sustained from a 2020 baseline near 2.48 billion USD, underscores the material's critical role in enabling high-frequency signal integrity across next-generation telecommunications and computing infrastructure. The market is no longer a niche supplier to PCB manufacturers; it has become a strategic bottleneck and enabler for the broader 5G ecosystem.
Despite the robust demand curve, the industry sits at a critical juncture defined by three interconnected challenges. First, raw material volatility is compressing margins and forcing reactive pricing strategies across the value chain. Second, geographic and supply chain concentration is creating strategic vulnerabilities, particularly as regulatory frameworks around critical minerals and processing technologies tighten. Third, the technical threshold for qualifying materials for millimeter-wave and sub-terahertz applications is rising, creating a barrier that favors entrenched players with advanced R&D pipelines while squeezing mid-tier manufacturers. The market is simultaneously expanding in volume and contracting in accessible entry points, a dynamic that will reshape competitive positioning over the next three to five years.
The structural shift is not merely about volume growth; it is about a redefinition of value capture. Historically, CCL competition revolved around cost efficiency and volume production. Today, the premium is shifting toward signal performance, thermal stability, and supply reliability. Companies that can decouple their competitive advantage from commodity resin and copper pricing will dictate the next cycle of industry consolidation. The pressure points are visible across the supply chain, from extended lead times and allocation tightening at key suppliers to material-specific price adjustments that reflect underlying chemical and textile cost inflation. These dynamics are transforming CCL procurement from a tactical purchasing function into a strategic risk management imperative.
Core Drivers Reshaping the Market Trajectory
The acceleration of 5G infrastructure deployment and the parallel densification of data center architectures form the foundational demand engine. High-frequency base stations, particularly those operating in millimeter-wave bands, require laminates with exceptionally low dielectric loss and stable thermal expansion coefficients. As telecom operators push toward network slicing, edge computing integration, and ultra-reliable low-latency communication, the performance bar for CCL materials continues to rise. This is not a linear upgrade cycle; each network generation introduces new signal integrity constraints that filter out legacy material formulations. The result is a structural pull toward advanced polymer systems that can maintain impedance control at higher switching speeds and under tighter thermal cycling.
Policy and regulatory environments are simultaneously acting as both accelerators and constraints. On one hand, national 5G rollout mandates, spectrum auctions, and industrial digitalization subsidies are injecting sustained capital into base station deployment and enterprise network upgrades. On the other hand, tightening export controls and critical material governance are reshaping procurement strategies. Regulatory actions on medium and heavy rare earth elements, alongside restrictions on related processing equipment and technologies, illustrate a broader shift toward material sovereignty. For CCL manufacturers and downstream system integrators, this means that supply continuity can no longer be assumed on globalized sourcing models alone. Strategic inventory positioning, regional qualification pathways, and multi-sourcing frameworks are becoming standard practice for operators seeking to insulate their roadmaps from policy-driven disruptions.
Worldwide High Frequency Hydrocarbon Copper Clad Laminate Market
Demand-side behavior is evolving beyond telecom infrastructure into adjacent high-growth verticals. Automotive electronics leveraging cellular vehicle-to-everything communication, high-performance computing clusters, and advanced packaging for data centers are all placing new requirements on CCL performance envelopes. The convergence of these applications creates cross-industry pull for materials that can serve both RF front-end and high-speed digital routing without compromising reliability. At the same time, supply chain and cost structures are undergoing a visible recalibration. Price adjustments across key raw material categories, including copper foil, glass fiber cloth, and epoxy-based systems, are pressuring cost models and prompting suppliers to rebalance capacity allocation. Recent material-specific price actions and extended lead times reflect a broader trend where availability and specification fidelity are increasingly valued over spot pricing.
Technological innovation continues to act as the differentiator that converts raw demand into sustainable market share. The pace of speed milestones in server and network equipment is forcing material scientists to push transmission loss lower while maintaining manufacturability. New material series targeting operation above 112 Gbps illustrate how performance breakdowns are being re-engineered at the resin, filler, and foil interface. These advances are not isolated product launches; they represent a structural shift toward materials engineered for co-design with high-speed SerDes channels, advanced packaging substrates, and phased-array antenna architectures. The companies that integrate material development with system-level simulation and qualification support will capture the highest-margin segments of the market.
Competitive Landscape and Strategic Positioning
The competitive field is characterized by a mix of established regional specialists and global technology leaders, with concentration metrics indicating that a limited number of players control a significant share of high-value output. The market structure favors companies that can combine scale with application-specific engineering, particularly in high-frequency, low-loss, and halogen-free formulations. The competitive edge is increasingly defined by three dimensions: material performance consistency, supply resilience, and ecosystem partnership depth.
Several firms have carved out clear strategic positioning. Japanese and Taiwanese technology leaders are emphasizing ultra-low transmission loss portfolios and multi-series platforms designed for mmWave antennas, high-speed network equipment, and advanced interconnect solutions. Their differentiation rests on long-standing resin chemistry expertise, extensive qualification track records, and the ability to co-develop materials alongside equipment OEMs. Chinese manufacturers, meanwhile, are executing aggressive capacity expansion to capture volume growth in 5G infrastructure and data center applications, leveraging localized supply chains and rapid scale-up capabilities. North American and European players are focusing on high-reliability segments where performance validation, regulatory compliance, and long-cycle procurement relationships create durable moats.
Recent corporate actions signal where strategic emphasis is intensifying. One major Japanese supplier introduced a new series of ultra-low transmission loss CCL materials within its flagship brand, explicitly targeting next-generation servers and network equipment operating above 112 Gbps. This move reinforces a performance-led strategy aimed at the premium segment where switching speed and signal integrity justify higher price points. In parallel, a leading Chinese producer announced construction of a dedicated facility for high-frequency and high-speed CCL, reflecting a deliberate push to secure capacity for 5G and data center demand. These developments illustrate a dual-track evolution: performance differentiation at the top end and capacity-led scale at the volume end.
The market is also showing signs of both consolidation and fragmentation, depending on the segment. High-performance, low-loss materials are trending toward concentration as qualification cycles lengthen and system designers prefer fewer, deeply integrated suppliers. Volume-oriented segments, by contrast, remain more competitive, with regional players competing on cost, delivery reliability, and localized technical support. New entrants face a steep curve because performance validation, copper foil and glass fiber sourcing relationships, and long-term procurement commitments create high switching costs. The practical implication for incumbents is that strategic advantage will come from locking in system-level partnerships, controlling critical input availability, and maintaining a pipeline of materials that anticipate the next speed and frequency thresholds.
PW Consulting
Forward Outlook: Trends Defining the Next Three to Five Years
The market's next phase will be shaped by the intersection of performance escalation, supply recalibration, and application convergence. Three trends stand out as particularly consequential.
First, ultra-low loss and multi-functional material platforms will become the default expectation for flagship 5G and edge infrastructure, not a premium differentiator. As base station architectures grow denser and parallel signaling speeds climb, materials that previously satisfied mid-tier requirements will be phased out of high-value designs. The commercial opportunity lies in offering application-matched grades that balance loss performance, thermal robustness, and manufacturability, rather than pursuing a single highest-specification product for every use case.
Second, supply chain resilience will be priced into procurement decisions. Extended lead times, allocation tightening, and input cost adjustments are shifting buyer priorities toward predictable availability and qualified secondary sources. Manufacturers that can demonstrate stable input sourcing, transparent capacity planning, and regional qualification support will command preference in constrained environments. This trend creates opportunities for suppliers that invest in vertical coordination, buffer strategies for critical inputs, and clear communication around allocation frameworks.
Third, cross-vertical material convergence will accelerate. The same underlying material science advances that serve 5G base stations are increasingly applicable to automotive connectivity, high-performance computing, and advanced packaging. Companies that can reposition material families across these applications, with appropriate qualification pathways and technical documentation, will unlock broader revenue pools and reduce cyclical dependency on any single end market. The risk is that rapid application expansion can strain qualification resources and blur focus if not managed with disciplined product segmentation.
Underlying these trends are uncertainties that demand scenario planning. Raw material cost trajectories, regulatory shifts affecting critical inputs, and the pace of next-generation speed adoption can each alter the timing and magnitude of demand realization. Overreliance on a single input category or a single application vertical amplifies exposure. The companies that navigate this period effectively will be those that treat material strategy as a dynamic system rather than a static product roadmap.
Actionable Guidance for Decision-Makers
For CCL and advanced materials manufacturers, the priority is to align capacity investments with performance-tier demand rather than pursuing undifferentiated volume. This means prioritizing ultra-low loss and application-specific formulations where qualification depth and co-development capabilities create pricing power, while simultaneously securing input availability for higher-volume grades through coordinated sourcing and transparent allocation practices.
For investors, the value creation map is shifting toward firms with credible pipelines in high-frequency, low-loss materials, strong technical support ecosystems, and resilient input strategies. Due diligence should focus on qualification momentum with system OEMs, the ability to sustain performance consistency across batches, and exposure to adjacent demand pools such as data center interconnects and automotive connectivity. Capacity expansion alone is insufficient without a clear path to differentiated performance and reliable delivery.
For procurement and engineering leaders, the practical move is to treat CCL selection as a multi-year strategic decision rather than a transactional purchase. Building dual-source qualification, aligning material specifications with anticipated speed and frequency roadmaps, and incorporating supply resilience criteria into vendor evaluations will reduce later-stage redesign risk and production disruption. Early engagement with suppliers on next-generation material grades can also accelerate qualification timelines and protect program schedules.
Strategic clarity in this market requires access to detailed segmentation insights, company-specific positioning data, and forward-looking scenario analysis that connect material performance trends with end-market demand cycles. Readers seeking deeper segmentation breakdowns, regional demand patterns, and customized strategic recommendations can explore the full PW Consulting research suite for structured data and tailored advisory support.
Copper Clad Laminate Market
For detailed analysis of this topic, please visit the official page: Worldwide Copper Clad Laminate for 5G Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
6.85% CAGR and $263M by 2032: The Low Energy Electron Gun Market's Key Growth Drivers Unpacked
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Low Energy Electron Gun Market
Market Status and Core Challenges
The worldwide low energy electron gun market has reached a mature inflection point, with global revenues climbing from approximately 144.5 million in 2023 to 164.88 million in 2025. Projections indicate steady expansion through 2032, with annual revenues expected to reach 263.03 million, translating to a compound annual growth rate of 6.85 percent across the 2026 to 2032 forecast horizon. This trajectory reflects a market that has moved beyond experimental validation and into routine deployment across high-value scientific and industrial workflows. Rather than chasing rapid, speculative growth, the sector is consolidating around applications where controlled, low-kinetic-energy electron beams deliver irreplaceable analytical precision and process reliability.
Neutron Generators Market
Despite this constructive backdrop, three structural challenges are reshaping how manufacturers and end-users approach procurement, product design, and operational deployment.
The first challenge centers on performance uniformity and standardization. Low energy electron guns serve as critical components in surface science instrumentation, semiconductor metrology platforms, and nanotechnology research setups, where even minor deviations in beam energy, spot size, or current stability can compromise measurement integrity. The industry relies on specialized calibration protocols that define uncertainty thresholds for kinetic energy scales, yet interoperability across vendor systems, aging infrastructure, and cross-platform data comparability remain persistent friction points. As research laboratories and advanced manufacturing lines increasingly integrate multi-instrument workflows, the absence of universally adopted performance baselines introduces procurement complexity and raises validation costs.
The second challenge involves regulatory compliance and operational licensing. Operating low energy electron beam systems often triggers jurisdictional radiation control requirements, ranging from import and installation approvals to ongoing compliance documentation. In certain regions, self-shielded systems demand explicit licensing, CE certification with documented risk analysis, and adherence to radiation protection frameworks. North American markets similarly require equipment suppliers and end-users to register with state or provincial radiation control authorities. These obligations extend time-to-deployment, elevate total cost of ownership, and create uneven competitive conditions for manufacturers that must navigate divergent regional frameworks while maintaining consistent product architectures.
The third challenge relates to cathode material constraints and vacuum compatibility requirements. Low energy electron guns depend on cathode formulations such as barium oxide, yttria-coated iridium, tantalum, and lanthanum hexaboride, each selected for specific emission characteristics and operating environments. Performance envelopes vary widely depending on vacuum levels, thermal management, and application duty cycles. As demand grows for higher current density, longer cathode life, and broader vacuum compatibility, suppliers face trade-offs between material cost, manufacturing precision, and field reliability. This dynamic is especially pronounced among smaller research buyers and emerging nanotechnology users, where procurement teams must balance specification requirements against budget limitations and long-term maintenance expectations.
Key Drivers of Market Change
A clear set of reinforcing drivers explains why the low energy electron gun market continues to expand at a resilient pace, even amid the challenges outlined above. The growth is not accidental; it emerges from converging shifts in technology capability, policy expectations, demand-side behavior, and manufacturing economics.
Technological innovation and source-design breakthroughs form the most immediate driver. The market increasingly rewards electron gun architectures that deliver tighter beam focusing, more stable low-energy operation, and flexible cathode configurations. Recent product catalog expansions reflect this direction, with suppliers introducing cathode options and system documentation that explicitly address low energy performance parameters, matching power supplies, and ultra-high-vacuum compatibility. These developments matter because analytical and deposition workflows are becoming more demanding. Surface science applications require reliable operation at low retarding energies, semiconductor metrology depends on repeatable beam characteristics for defect inspection and process control, and nanotechnology research increasingly integrates low-energy sources into multi-modal characterization platforms. Manufacturers that can offer configurable systems—spanning thermionic, field emission, and photoemission principles—capture broader demand while maintaining technical credibility in specialized end-use sectors.
Policy and regulatory evolution is another powerful driver, though its impact operates through compliance burden rather than direct demand stimulation. Radiation protection rules, import and installation licensing structures, and standardized calibration expectations shape purchasing decisions and product roadmaps. Standardization frameworks for kinetic energy calibration, sterilization process requirements, and regional registration obligations create a compliance landscape that favors vendors with mature documentation practices, traceable calibration support, and strong application engineering teams. In practical terms, this shifts buying preference away from lowest-unit-cost offerings and toward suppliers that can reduce integration risk, simplify regulatory navigation, and provide defensible performance validation. The result is a market where technical support and compliance readiness are becoming core differentiators alongside hardware specifications.
Demand-side changes are equally significant. Research institutions, advanced materials companies, and semiconductor manufacturers are steadily increasing their reliance on low-energy electron beam tools for surface analysis, thin-film characterization, and precision metrology. Rather than treating these instruments as occasional-use equipment, many organizations now embed them into recurring analytical workflows, which improves utilization rates and justifies higher specification thresholds. At the same time, imaging and industrial processing applications continue to adopt low energy beam configurations for specialized tasks that benefit from controlled deposition, charge neutralization, and localized treatment. This broadening use pattern reduces dependence on any single vertical and encourages modular system design, custom engineering, and application-specific tuning.
Supply chain and cost structure dynamics complete the picture. Electron gun components remain closely tied to specialized cathode materials, precision machining, vacuum-compatible assembly, and high-performance power supply integration. Recent pricing adjustments in product lines and related vacuum components highlight how material cost movements, component availability, and fabrication complexity influence end-market pricing. For buyers, this translates into greater sensitivity to total lifecycle cost rather than initial purchase price alone. For manufacturers, it reinforces the value of stable cathode sourcing strategies, improved yield in brazing and assembly processes, and inventory planning that accounts for long lead times on critical subcomponents. Companies that manage these cost levers effectively can preserve margin while remaining competitive in specification-driven procurement.
Competitive Landscape and Leading Strategies
The competitive environment in the low energy electron gun market is defined by a mix of specialized system providers, established instrument manufacturers, and application-focused suppliers. Market concentration remains moderate, with the top three firms accounting for roughly 48.5 percent of sector revenues and the top five approaching 62.2 percent. This structure indicates a landscape where incumbents hold meaningful share but differentiation is still achievable through product flexibility, application coverage, and compliance readiness.
Leading players have carved out distinct strategic positions. Several U.S.-based manufacturers emphasize configurable electron gun systems with broad operating ranges, multiple cathode options, and custom project support for surface science and vacuum applications. Their approach centers on modular flexibility, enabling buyers to match source characteristics to specific experimental requirements while maintaining ultra-high-vacuum compatibility. In parallel, European suppliers have built reputations around comprehensive electron source portfolios spanning low-, medium-, and high-energy categories, with strong emphasis on beam control features such as blanking, pulsing, computer control, and integration into analytical workflows like Auger electron spectroscopy and electron light scattering. This breadth allows them to serve both research and industrial customers who require more than a single-purpose source.
Other participants position around manufacturing precision and component-level expertise. One U.S. company focuses on electron gun assemblies and cathodes for vacuum technology, lithography, and accelerator contexts, offering both standard and custom models with high current density emitters. Another emphasizes high-precision brazed components and replacement units for linear accelerator applications, with engineering capabilities that extend into lower-energy configurations where accelerator platforms intersect with specialized beam needs. A separate group of suppliers targets surface analysis instrumentation directly, providing compact electron guns and sources optimized for low-energy retarding modes and techniques such as LEED and RHEED. These companies compete by aligning product form factors with the practical constraints of laboratory space, integration complexity, and instrument-level performance.
Broader instrumentation and electron optics expertise also shape the competitive field. Japanese manufacturers bring established know-how in electron beam sources for industrial deposition and electron optics for microscopy and lithography systems, which creates natural adjacency to low-energy beam applications. Large multinational scientific instrumentation providers contribute through high-resolution imaging and materials analysis platforms that incorporate low-energy electron gun capabilities, leveraging scale, service networks, and software integration to support demanding laboratory environments. Together, these players illustrate how the market rewards both specialization and ecosystem breadth.
Recent developments reinforce the ways in which incumbents defend and extend their positions. Price adjustments in electron gun products and related vacuum components signal how suppliers are managing cost pressures while preserving value positioning. Product catalog updates and new cathode compatibility expansions demonstrate continued attention to material options and specification clarity, which matters in a market where matching the source to the application is often more important than the hardware brand alone. Documentation updates that consolidate low energy system details further indicate an industry-wide emphasis on reducing specification ambiguity and shortening customer evaluation cycles.
PW Consulting
Looking across these dynamics, two competitive trends are becoming clearer. First, differentiation is shifting from pure hardware specification toward application reliability, calibration support, and regulatory readiness. Second, the market is simultaneously consolidating around established players with broad portfolios and fragmenting at the application level, where custom engineering and niche cathode or source configurations create room for focused specialists. New entrants that can deliver credible performance, clean documentation, and strong integration support may find opportunities in underserved applications, but they will need to navigate stringent compliance expectations and a buyer base that increasingly prioritizes validated results over incremental cost savings.
Future Trends and Commercial Opportunities
Over the next three to five years, the low energy electron gun market is likely to be shaped by three interconnected trends, each of which carries distinct commercial implications. The first trend is specification convergence around tighter energy control, improved source longevity, and clearer calibration alignment. As analytical and metrology workflows become more standardized across laboratories and production environments, buyers will increasingly prioritize sources that reduce measurement uncertainty and simplify cross-instrument comparability. Commercial opportunity lies in vendors that can provide traceable calibration support, robust documentation, and system configurations that integrate smoothly with existing instrumentation while maintaining consistent low-energy performance.
The second trend is the growing reliance on application-tailored configurations rather than one-size-fits-all products. Surface science, semiconductor metrology, nanotechnology research, and specialized imaging applications each impose different beam requirements, vacuum conditions, and duty cycles. This reduces the effectiveness of generic hardware offerings and increases the value of modular design, multiple cathode options, and rapid custom engineering. In this environment, suppliers that can shorten configuration cycles, provide clear application guidance, and maintain reliable delivery timelines are well positioned to capture high-value projects and recurring instrument-level demand.
The third trend is the continued elevation of compliance and integration risk as purchasing criteria. Regional licensing, radiation control registration, and certification requirements are not disappearing; they are becoming embedded into procurement due diligence. Buyers will favor suppliers that reduce deployment friction through clear documentation, validated safety and risk analysis practices, and dependable service support. Commercial opportunity will flow to organizations that treat compliance as part of the product experience rather than an afterthought. At the same time, this trend introduces risk: companies that depend on a narrow set of cathode materials or specialized subcomponents may face margin pressure if supply conditions tighten or if regulatory expectations become more stringent across multiple jurisdictions.
Strategic Recommendations for Decision-Makers
For manufacturers and system developers, the priority is to treat low energy electron gun offerings as application solutions rather than standalone components. This means investing in cathode option breadth, power supply integration, and documentation that reduces ambiguity for buyers evaluating low energy performance. Equally important is building compliance-ready product narratives that help customers navigate licensing, registration, and calibration expectations without adding procurement friction. Companies that can combine specification flexibility with reliable delivery and strong support will capture more project work and improve reuse of engineering assets across applications.
For investors, the most attractive signals are recurring demand in surface analysis and semiconductor metrology, increasing utilization of low energy beam tools in multi-instrument workflows, and value migration toward suppliers that reduce compliance and integration risk. Capital allocation should favor organizations with stable cathode and vacuum-compatible component strategies, credible calibration and documentation practices, and portfolios that can serve both research and industrial buyers. Exposure to single-application or single-material dependencies deserves closer scrutiny, especially where pricing pressure and supply variability could compress margins.
For procurement and technical buyers, the strategic question is less about finding the lowest initial cost and more about minimizing total deployment risk. Evaluation criteria should include cathode compatibility with intended vacuum conditions, beam stability at low energies, calibration support, and the supplier’s ability to provide clear regulatory and integration guidance. Where applications are specialized, the ability to configure or customize source and power supply pairing can matter more than brand familiarity. Buyers that structure evaluation around operational reliability, documentation clarity, and long-term serviceability are better positioned to avoid costly rework and delayed deployment.
E Beam Accelerators Market
As the market continues its steady expansion, the most valuable intelligence is the kind that connects market sizing, application demand, competitive positioning, and compliance dynamics into a decision-ready view. Access to the full research report provides more granular segmentation data, detailed company comparisons, and customized guidance tailored to specific commercial objectives, making it a practical next step for teams seeking to act on the trends outlined here.
For detailed analysis of this topic, please visit the official page: Worldwide Low Energy Electron Gun Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stern Drive Boat Propeller Market: Why 6.7% CAGR Reshapes the $3.57B Outlook to 2032
By pmarketresearch, 2026-09-18
Stern Drive Boat Propeller Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The stern drive boat propeller market has demonstrated resilient expansion over the past half-decade, reaching an estimated valuation of USD 3,567.0 million in 2025. Historical data from 2020 through 2025 indicates a compound annual growth rate of 6.7 percent, positioning the sector on a solid trajectory toward USD 5,616.39 million by 2032. This growth reflects steady demand across recreational and commercial marine segments, alongside incremental technological upgrades that enable vessels to achieve better fuel efficiency and maneuverability. As marine propulsion systems evolve, the propeller component remains a critical interface between engine performance and hydrodynamic efficiency, making it a focal point for manufacturers and buyers alike.
Despite the favorable overarching trajectory, the industry faces several structural challenges that demand strategic attention. First, material cost volatility introduces pronounced uncertainty into pricing and margin forecasting. Raw material markets, particularly nickel-based alloys used in corrosion-resistant propeller designs, have experienced notable price swings between 2024 and 2025. Such fluctuations compress profitability for manufacturers operating on fixed-price contracts while simultaneously pressuring downstream buyers who seek predictable procurement costs. Second, the market exhibits moderate concentration, with the top three firms accounting for approximately 38.5 percent of total revenue and the top five controlling roughly 52.8 percent. This landscape creates both competitive stability and barriers for emerging players, particularly when established incumbents leverage decades of OEM relationships, proprietary hub architectures, and extensive aftermarket distribution networks. Third, the shift toward electrified and hybrid marine propulsion systems is gradually reshaping performance requirements. Traditional stern drive configurations must adapt to new torque curves, weight constraints, and acoustic expectations, compelling propeller designers to reconsider blade geometry, cavitation behavior, and integration standards.
For strategic decision-makers, these dynamics suggest that market participation requires more than scale alone. Success increasingly depends on material sourcing agility, technical differentiation, and the ability to align product portfolios with evolving vessel architectures. Organizations that anticipate these shifts rather than react to them are better positioned to capture share in both OEM channel development and aftermarket replacement cycles.
The intersection of growth momentum and structural complexity defines the current operating environment. Market participants must balance near-term revenue opportunities against longer-term technology transitions, while navigating cost pressures that affect both production economics and end-customer affordability. Understanding these forces is essential for prioritizing capital allocation, partnership strategies, and product roadmaps.
Key Drivers of Market Evolution
Three interconnected forces are shaping the directional path of the stern drive propeller market: material innovation, regulatory and environmental expectations, and shifting demand-side behavior in both recreational and commercial marine segments. Each driver carries distinct implications for product design, supply chain planning, and competitive positioning.
Material Innovation and Performance Optimization
Material selection continues to influence durability, weight, and operational efficiency across stern drive propeller applications. Aluminum and stainless steel formulations remain dominant in the market, with aluminum propellers representing the largest material category by revenue and stainless steel offering enhanced wear resistance for higher-performance applications. Alongside these mainstream materials, advanced nickel-aluminum bronze and specialty alloys retain importance for applications demanding superior corrosion resistance in saltwater environments. The breadth of material options allows manufacturers to tailor offerings to specific duty cycles, vessel weights, and propulsion loads.
Recent product activity underscores the strategic importance of material engineering and blade configuration. Michigan Wheel has reinforced its focus on core North American segments following the strategic divestiture of its United Kingdom operations to Nakashima Propeller, sharpening its attention on aluminum and stainless steel profiles compatible with major sterndrive platforms. This realignment reflects a broader pattern in which manufacturers concentrate resources on markets where OEM integration and aftermarket demand provide the strongest return on engineering investment. Meanwhile, Solas has emphasized renewed product visibility around both outboard and sterndrive propeller lines, signaling continued investment in material-grade differentiation and hub system compatibility such as RUBEX configurations.
From a commercial perspective, material-driven innovation affects more than technical specifications. It influences lead times, inventory planning, and dealer-level service capabilities. Manufacturers that stabilize alloy sourcing while offering clearly differentiated performance tiers can better manage cost volatility and present compelling upgrade paths to boat builders and fleet operators.
Regulatory and Environmental Pressures
Marine environmental standards and emissions expectations are gradually influencing propulsion system design, which in turn affects propeller engineering. While stern drive systems are not subject to the same regulatory intensity as automotive powertrains, broader maritime efficiency goals and local water-quality initiatives contribute to a performance mindset that favors reduced fuel consumption, lower vibration, and improved hydrodynamic behavior. These priorities encourage propeller designs that maximize thrust efficiency without increasing engine strain.
The regulatory environment also interacts with material choices. Corrosion resistance, service life, and recyclability are increasingly considered in procurement decisions for commercial fleets and high-use recreational vessels. Operators seek components that reduce downtime and maintenance exposure, particularly in regions where seasonal usage compresses available operating windows. Consequently, product longevity and reliability have become important selling points alongside raw performance metrics.
Demand-Side Shifts in Recreational and Commercial Segments
Recreational boating remains the largest application segment in the market, reflecting sustained consumer interest in leisure marine activities and aftermarket replacement cycles. Buyer behavior in this segment increasingly favors performance upgrades, easier installation compatibility, and visually distinctive blade profiles that align with customized boat configurations. At the same time, commercial operators prioritize durability, predictable maintenance intervals, and compatibility with existing drive families, especially where fleet standardization reduces training and parts complexity.
Within this demand landscape, product specialization is gaining traction. Sharrow Marine has extended testing and rollout activity for its looped propeller designs, including configurations intended for dual-prop sterndrive setups used with major drive platforms. This approach illustrates a broader trend: rather than competing solely on material grade, some manufacturers are pursuing aerodynamic and hydrodynamic geometry as a source of differentiation. The commercial relevance lies in the potential for improved efficiency and reduced vibration, which can appeal to both performance-oriented recreational buyers and commercial users seeking operational savings over long service intervals.
Supply Chain and Cost Structure Dynamics
Supply chain stability remains a defining concern for propeller manufacturers and downstream buyers. Fluctuations in key input costs, particularly for nickel-bearing alloys, have periodically reshaped pricing strategies and margin planning. Between 2024 and 2025, nickel-related pricing moved within a wide band, creating variable cost conditions for manufacturers producing corrosion-resistant propeller lines. This environment rewards companies with diversified sourcing strategies, forward procurement arrangements, and flexible production scheduling.
Cost structure pressures also influence the balance between standardized and customized offerings. High-volume standardized propeller families support efficient production and broader aftermarket availability, while specialized blade geometries and hub systems require more focused engineering and lower-volume runs. Companies that can maintain efficient core production while selectively introducing differentiated variants are better equipped to serve mixed demand without sacrificing margin integrity.
Competitive Landscape and Leading Strategies
The competitive environment in the stern drive propeller market is characterized by a blend of OEM-aligned suppliers, independent performance specialists, and integrated drive system manufacturers. The presence of both established marine propulsion names and focused propeller innovators creates a multifaceted landscape where differentiation can emerge from material technology, compatibility breadth, brand trust, or structural design innovation.
Strategic Positioning Among Key Players
Michigan Wheel occupies a prominent position through its extensive aluminum and stainless steel portfolio designed for sterndrive applications and its strong compatibility with widely used drive platforms. Its recent strategic decision to divest UK operations reflects a deliberate concentration on core market segments where distribution reach and aftermarket support provide durable advantage. By prioritizing compatibility and breadth of blade options, the company reinforces its role as a practical partner for both OEM integration and replacement demand.
Sharrow Marine differentiates itself through patented looped propeller technology and an emphasis on efficiency-oriented performance. Its continued expansion into dual-prop sterndrive configurations indicates a strategy centered on product architecture rather than commodity material competition. For buyers evaluating efficiency gains and refined handling characteristics, this positioning offers a distinct value proposition that complements traditional product categories.
Solas maintains a broad manufacturing footprint and strong compatibility across multiple sterndrive engine families, supported by hub technologies such as RUBEX systems. Its recent product display activity highlights ongoing attention to both outboard and sterndrive propeller lines, reinforcing its ability to serve multi-platform demand. Volvo Penta and Mercury Marine, as major OEM players, leverage their integrated system expertise to offer propellers that align closely with dedicated drive architectures, including counter-rotating and multiple blade configurations optimized for their respective units. This OEM alignment provides a strong baseline for compatibility trust, particularly among buyers seeking seamless system performance.
Marine Propeller Market
Several independent manufacturers, including Turning Point Propellers, PowerTech Propellers, Konrad Marine, and Hill Marine, add further diversity to the market. Their focus areas range from high-quality aluminum and stainless steel profiles to performance stainless steel designs and heavy-duty commercial applications. This breadth allows buyers to select from a range of price-performance points, while also creating opportunities for specialized distributors and service networks.
Market Structure and Evolution Trends
The market remains moderately consolidated, but it is not static. Consolidation pressures may continue in areas where scale, OEM access, and global distribution confer durable advantages. At the same time, product innovation and niche application focus create room for differentiation even in a concentrated environment. The most notable evolution is the increasing importance of technology-led positioning: companies are competing not only on material and compatibility, but also on blade geometry, vibration reduction, and application-specific tuning.
Another emerging trend is the interplay between OEM channels and independent aftermarket demand. While OEM relationships provide volume stability, aftermarket replacement and performance upgrades can offer higher margin opportunities and faster product iteration cycles. Manufacturers that manage both channels effectively are able to balance predictable volume with selective premium offerings. This dual-channel capability is increasingly important as recreational boat owners seek upgrade paths and commercial operators evaluate lifecycle cost rather than initial purchase price alone.
Geographic dynamics also matter, though competitive advantage is often determined less by regional volume leadership than by proximity to major boat-building clusters, service infrastructure, and drive-platform ecosystems. Firms with strong operational presence in key North American and European marine markets benefit from shorter feedback loops with boat builders and faster response to regional product preferences. Meanwhile, manufacturers with multi-region production and distribution capabilities can better manage supply continuity and currency exposure in a volatile input-cost environment.
PW Consulting Automotive & Machinery Research Center
For commercial strategists, the key question is not simply who holds the largest share today, but which companies can sustain differentiation through product engineering, channel flexibility, and cost control. Competitive success will likely favor organizations that can align proprietary design advantages with reliable supply execution and clear compatibility messaging.
Forward-Looking Trends and Commercial Implications
Looking ahead across the 2026 to 2032 horizon, the stern drive propeller market is likely to be shaped by three broad movements: incremental efficiency-focused product design, more segmented material strategies, and a continued rebalancing between OEM integration and aftermarket specialization. These trends are not independent; each reinforces the others and influences how manufacturers, distributors, and end users allocate resources.
First, efficiency-oriented propeller design is expected to gain further prominence. Buyer sensitivity to fuel consumption, noise, and handling refinement supports continued interest in blade geometry innovations and dual-prop configurations where applicable. As more vessels adopt modern drive platforms and operators seek operational savings, products that deliver measurable performance improvements without compromising compatibility will likely find strong market receptivity. This creates opportunities for companies that can substantiate performance claims with clear testing and application-specific guidance.
Second, material strategies are likely to become more segmented. Broad-based aluminum and stainless steel portfolios will remain important for volume and compatibility, but specialized alloys and corrosion-resistant formulations will continue to matter for demanding environments and longer service life expectations. Cost volatility in key inputs will reward suppliers that can balance efficiency in standard production with selective premium offerings for high-value applications. In practice, this means more deliberate segmentation between mainstream replacement products and performance or commercial-grade lines.
Third, the relationship between propulsion system evolution and propeller design will intensify. Even if full electrification remains a gradual transition in sterndrive applications, hybrid configurations and revised torque characteristics will influence blade loading, hub requirements, and integration tolerances. Manufacturers that invest early in understanding these interaction points will be better prepared to support next-generation drive families and to reduce time-to-market for new compatible propeller lines.
These trends carry commercial opportunity, but they also introduce uncertainty. Material price swings, changing regulatory emphasis, and the pace of propulsion system modernization can all alter the speed and direction of demand. For investors and executives, the practical implication is that long-range planning should account for both baseline growth and scenario variability, especially where product roadmaps depend on input cost stability or specific drive-platform adoption patterns.
Strategic Recommendations for Decision-Makers
For manufacturers, the most effective strategy is to pursue disciplined differentiation rather than undifferentiated volume expansion. Strengthening compatibility with widely used sterndrive platforms, stabilizing material sourcing for corrosion-resistant lines, and developing clear performance narratives around efficiency and durability can help protect margins in a competitive environment. Companies should also evaluate channel balance carefully, ensuring that OEM relationships and aftermarket distribution complement rather than conflict with one another.
For investors, the priority is to identify businesses with defensible technical positions, flexible cost structures, and demonstrated ability to serve both established drive ecosystems and emerging performance niches. In a market where material volatility and product specialization both matter, firms with strong engineering execution and channel resilience are better positioned to sustain earnings through cycles. Due diligence should extend beyond headline revenue trends to include product pipeline relevance, hub and compatibility strategies, and exposure to input-cost sensitivity.
For procurement leaders and fleet operators, the focus should be on total lifecycle value rather than unit price alone. Compatibility assurance, predicted service life, maintenance impact, and supplier responsiveness all influence long-term operating costs. Standardizing on propeller families that align with existing drive platforms can reduce complexity, while selectively adopting higher-efficiency or higher-durability variants can improve performance where usage intensity justifies the investment. Maintaining visibility into supplier roadmaps and material availability will also support more resilient procurement planning.
For stakeholders seeking deeper segment-level data, regional revenue splits, application-level dynamics, and detailed competitive benchmarking, the full PW Consulting report provides a more granular view of market structure and forward scenarios. Detailed segmentation data and tailored strategic guidance can help translate these market-level observations into actionable plans aligned with specific product portfolios, geographies, and operating models.
Airplane Propellers Market
For detailed analysis of this topic, please visit the official page: Stern Drive Boat Propeller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Anti-Emetic Drug Market: Why 4.85% CAGR Growth Redefines Oncology Demand
By pmarketresearch, 2026-09-18
Beyond Nausea Control: Strategic Shifts in the Global Anti-Emetic Drug Market
Market Landscape: Size, Growth, and Structural Challenges
The global anti-emetic drug market has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately 3,314 million in 2020 to an estimated 4,200 million in 2025. This trajectory reflects a compound annual growth rate of 4.85 percent across the historical period, with projections indicating the market will reach 5,850 million by 2032. The growth is not merely a function of population aging or increased healthcare access; it is driven by deeper clinical integration of anti-emetic protocols into oncology, surgical care, and chronic gastrointestinal management. Revenue streams have become increasingly tied to standardized prophylaxis regimens, particularly in highly emetogenic chemotherapy settings where treatment adherence and patient quality of life directly influence clinical outcomes.
Despite the upward trajectory, the industry is navigating three structural inflection points that will define competitive positioning over the next cycle. The first is the tension between volume expansion and margin compression. As foundational molecules lose intellectual property protection, pricing pressure intensifies across mature therapeutic classes, forcing manufacturers to balance high-volume generic distribution with targeted branded innovation. The second challenge lies in regulatory complexity layered onto clinical deployment. Risk evaluation and mitigation strategies now accompany certain active ingredients, requiring healthcare providers to manage administrative compliance alongside dosing protocols. This adds friction to formulary adoption, particularly in institutions where pharmacy and therapeutics committees prioritize streamlined procurement pathways. The third inflection point is supply chain volatility. Recent intermittent shortages of widely used anti-emetics highlighted the fragility of concentrated manufacturing bases and the downstream impact on hospital scheduling, outpatient clinics, and community oncology practices. The resolution of these disruptions required coordinated production scaling, but the episode underscored how quickly formulary substitutions and therapeutic alternatives become necessary when inventory gaps emerge.
For decision-makers, these dynamics signal a market that is growing but structurally maturing. Expansion will increasingly come from optimized clinical pathways, formulation innovation, and strategic pricing architectures rather than from broad-based volume growth alone. Companies that treat anti-emetics as commoditized supportive care products risk being squeezed by margin erosion and formulary displacement. Those that align product architecture with real-world administration constraints, procurement cycles, and reimbursement mechanics are better positioned to capture sustained share.
Strategic Drivers Reshaping Demand, Innovation, and Commercial Architecture
Several interlocking forces are accelerating change in how anti-emetic therapies are developed, priced, prescribed, and distributed. The most visible driver is clinical innovation centered on receptor-targeted combinations and extended-delivery formulations. Fixed-dose pairing of neurokinin-1 and serotonin antagonists has gained traction for chemotherapy-induced nausea and vomiting prophylaxis, while prolonged-release injectable formats address gaps in dosing adherence for highly emetogenic regimens. Pediatric-specific formulation work has also progressed, reflecting the recognition that supportive care protocols cannot simply scale down adult dosing without pharmacokinetic and tolerability calibration. These clinical refinements create differentiation beyond active ingredient competition and support premium positioning where efficacy, convenience, and regimen simplification resonate with oncologists and surgical teams.
Anti-tumor Drug Market
Regulatory and reimbursement architecture forms the second major driver. Policy requirements around safety monitoring, adverse event reporting, and restricted-distribution frameworks influence both market access and operational burden. At the same time, pricing benchmarks tied to average sales prices and wholesale acquisition cost structures place downward pressure on mature molecules, while creating transparency that payers and hospital procurement teams increasingly use in formulary negotiations. The effect is a bifurcated commercial environment: older therapeutic classes face aggressive generic substitution and price erosion, while newer or combination formulations rely on clinical differentiation and service-oriented adoption support to maintain value.
Demand-side behavior is evolving in parallel. Oncology centers, surgical suites, and gastroenterology practices are placing greater emphasis on proactive nausea control as a determinant of treatment continuity, early hospital discharge, and patient satisfaction. This shifts procurement logic from unit-price evaluation toward total episode cost and adherence outcomes. Buyers are increasingly comparing regimens based on administration frequency, rescue medication utilization, and compatibility with existing chemotherapy protocols. The clinical conversation has moved beyond whether to prevent nausea to how to minimize downstream interruptions in therapy, which favors products and service models that integrate smoothly into high-throughput care settings.
Supply chain and cost structure dynamics complete the driver set. Manufacturing concentration, active pharmaceutical ingredient availability, and regional production capacity influence market resilience. When global supply disruptions occur, the response depends on the speed at which multiple producers can scale output and on regulatory mechanisms that identify and prioritize shortage resolution. Cost structures are also being reshaped by geographic diversification of generic manufacturing and shifting procurement strategies that blend volume commitments with contingency sourcing. These factors matter because anti-emetic procurement often operates as a predictable recurring expense for healthcare systems, and any break in continuity can cascade into operational friction and therapeutic substitution costs.
Taken together, these drivers suggest that competitive advantage will increasingly belong to organizations that can connect clinical innovation with market access discipline. The winning playbook involves formulation differentiation, proactive regulatory engagement, procurement-aligned pricing, and supply resilience that reduces exposure to intermittent shortages.
Competitive Positioning and the Evolution of Market Structure
The competitive field in the anti-emetic market spans multinational innovation leaders, established branded franchises, and broad generic portfolios. Companies with NK1 receptor antagonist platforms have built commercial strength around chemotherapy-induced nausea and vomiting prevention, often leveraging label expansion to cover additional emetogenic regimens and patient populations. Meanwhile, the most widely deployed 5-HT3 antagonist portfolios have long served as foundational options in post-operative and oncology settings, supported by extensive clinical familiarity and broad distribution networks. Several Swiss and U.S. players maintain positions through fixed-dose combinations or extended-release variants, aiming to improve adherence and reduce dosing complexity. Other participants compete through high-volume generic manufacturing of ondansetron, granisetron, and related molecules, emphasizing affordability, formulary breadth, and supply availability across multiple markets.
Strategic differentiation among leading firms is increasingly defined by portfolio architecture rather than single-molecule dominance. Branded leaders tend to invest in clinical evidence generation, regimen-specific label positioning, and targeted patient population expansion, including pediatric and specialty oncology cohorts. Generic-focused participants differentiate through manufacturing scale, pricing agility, and multi-market distribution, making them essential partners for hospital systems seeking cost control and continuity of supply. Combination and extended-release offerings create a middle ground, allowing developers to compete on convenience and prophylaxis durability rather than raw molecule novelty alone. The commercial result is a layered competitive landscape where brand-level differentiation, generic substitution, and formulation innovation coexist in the same therapeutic category.
Market structure is evolving along several clear trends. Patent expirations in widely used older molecules continue to open the door to generic entrants, compressing pricing and shifting revenue composition toward volume-driven sales in mature segments. At the same time, targeted approvals and label updates in specialized indications preserve room for premium positioning where clinical need and regimen complexity justify differentiation. Recent milestones illustrate this pattern: regulatory approvals for pediatric formulations broaden addressable populations in supportive care, positive late-stage trial readouts for new NK1 candidates sustain the innovation pipeline, and label expansions widen the clinical footprint of established branded assets. Conversely, generic launches following patent expiry in combination formulations demonstrate how quickly value can shift once exclusivity ends.
The market is also showing signs of pragmatic consolidation and specialization. Large diversified pharmaceutical companies maintain anti-emetics as part of broader oncology and supportive care portfolios, using cross-portfolio integration to strengthen formulary positioning and sales coverage. Specialist and mid-sized players often concentrate on niche value propositions, such as extended-release delivery or specific prophylaxis combinations, where focused clinical messaging can outweigh scale advantages. At the same time, generics manufacturers continue to expand capacity and global distribution, reinforcing their role as the structural backbone of accessible supportive care.
For executives evaluating this landscape, the key insight is that competitive success is no longer determined by molecule ownership alone. It depends on the ability to align therapeutic positioning with procurement realities, manage regulatory and reimbursement constraints, and maintain reliable supply in a category where continuity directly affects clinical workflows. Differentiation will increasingly come from formulation design, evidence packaging, access strategy, and supply reliability rather than from a single winner-takes-all asset.
Outlook: The Next Wave of Growth, Disruption, and Commercial Opportunity
Looking toward the 2026 to 2032 horizon, three developments are likely to shape market direction. The first is a continued shift from reactive symptom management toward standardized prophylactic regimens embedded in chemotherapy and surgical pathways. As clinical teams prioritize reducing treatment interruptions and improving patient experience, demand should remain concentrated around molecules and combinations that deliver durable control with manageable administration burden. This creates commercial opportunity for products and protocols that can demonstrate real-world adherence benefits and lower downstream rescue medication use, especially in high-emetogenic settings.
Nausea and Vomiting Treatment Market
The second trend is the ongoing repricing of mature categories alongside selective premium positioning in differentiated segments. Generics will remain the price anchors across broad anti-emetic use, but combination therapies, extended-release formats, and indication-specific formulations will continue to support value capture where clinical justification and formulary alignment exist. The commercial implication is that pricing strategy must be segmented carefully: volume and cost efficiency will drive generic share, while evidence, convenience, and access support will determine premium adoption. Procurement teams will increasingly evaluate these segments through total-cost lenses rather than unit price alone.
The third trend is greater emphasis on supply resilience and formulation diversification. Intermittent shortages have demonstrated that even well-established molecules can face availability constraints when manufacturing, demand surges, or regulatory actions intersect. This encourages broader sourcing strategies, dual-supplier arrangements, and regional production planning among healthcare systems and distributors. For manufacturers, it creates a strategic premium for operational reliability and for participants who can demonstrate consistent capacity, transparency, and responsiveness during demand volatility.
These trends carry both opportunity and uncertainty. Growth prospects are supported by expanding oncology volumes, surgical caseloads, and supportive care standardization, but they are tempered by persistent margin pressure in generic-heavy segments and evolving regulatory and reimbursement expectations. Companies that can combine clinical differentiation with procurement-aware pricing and robust supply planning are best placed to navigate this environment. Those relying solely on volume without access strategy may find share growth offset by pricing erosion and substitution pressure.
Decision-Maker Playbook: Positioning for Value in a Maturing Category
For manufacturers and brand leaders, the priority is to reinforce differentiation where it translates into formulary preference and clinical adoption. That means investing in regimen-specific evidence, expanding indications and population coverage where clinically defensible, and designing access strategies that reflect average pricing benchmarks and procurement cycles. Formulation innovation that reduces administration burden or improves adherence should be framed in practical care-pathway terms rather than as isolated product features. Supply continuity planning should also be treated as a commercial asset, not just an operational function, because reliability increasingly influences purchasing decisions in high-throughput oncology and surgical settings.
For investors, the market rewards disciplined exposure to differentiated supportive care assets and scalable generic operations. The clearest opportunities lie in portfolios that combine clinical relevance with cost-efficient manufacturing, and in companies that can manage the transition from exclusivity to competitive positioning without eroding margin structure. Pipeline readouts, label expansion potential, and formulation milestones matter, but so does the ability to anticipate pricing dynamics following patent events and to assess supply chain exposure across active ingredients and production geographies. Due diligence should account for reimbursement architecture, procurement sensitivity, and the operational cost of maintaining continuity in a category where shortages can quickly reshape purchasing behavior.
For procurement teams and healthcare operators, the strategic task is to balance cost control with therapy continuity and clinical outcomes. That involves evaluating anti-emetic regimens as part of total episode management, comparing options based on dosing frequency, prophylaxis durability, rescue utilization, and supply reliability, rather than selecting purely on lowest unit price. Formulary design should incorporate contingency planning for shortage scenarios and acknowledge the administrative burden associated with safety monitoring requirements for certain molecules. The goal is to protect patient access and workflow stability while managing expenditure in a category that remains essential to oncology, surgical, and gastrointestinal care.
The strategic stakes in this market are rising as growth becomes more segmented and competitive advantage shifts toward execution quality across clinical positioning, access architecture, and supply resilience. Working-level teams seeking to translate these dynamics into procurement, investment, or product strategy will benefit from a more granular view of regional demand patterns, segment-level volume and pricing trends, and scenario analysis around patent events, reimbursement shifts, and shortage risk. A deeper research dossier can provide that level of detail, including breakouts by region, drug class, application, and company-level competitive mapping, to support more precise planning and prioritization.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Anti-Emetic Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Fisetin Market: How 8.96% CAGR and Supplement Demand Reshape 2032 Revenue
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Fisetin Market
Market Overview and Core Challenges
The global fisetin market has transitioned from a niche botanical extract to a high-value ingredient category, driven by accumulating clinical and preclinical evidence around its senolytic, anti-inflammatory, and metabolic-modulating properties. Between 2020 and 2025, the market expanded from approximately USD 38.45 million to USD 57.8 million, reflecting a structural shift rather than a cyclical uptick. Forward projections extending through 2032 indicate a compound annual growth rate of 8.96 percent, positioning fisetin as a sustained growth vector within the broader functional ingredients landscape. Revenue trajectory suggests that by 2032, global market size will approach USD 105.42 million, a level that underscores maturation but also signals intensifying competition for market share.
This growth trajectory is not without friction. The industry currently faces several structural challenges that will define the next phase of market evolution. First, purity standardization and bioequivalence remain unresolved . Fisetin exhibits variable extraction yields and stability profiles depending on the plant source, solvent method, and downstream processing. Without universally accepted pharmacopeial standards, manufacturers and formulators face uncertainty in dosing consistency, which complicates both regulatory submissions and consumer trust. Second, raw material sourcing is under transition . Traditional trunk-based extraction is increasingly being replaced by leaf and branch sourcing from Cotinus coggygria or Rhus succedanea , a shift designed to improve yield per hectare, reduce ecological impact, and lower unit costs. While this transition supports scaling, it introduces variability in active content and requires tighter quality control frameworks. Third, geopolitical and trade dynamics are reshaping cost structures . Ongoing tariff policies on certain botanical and chemical imports, particularly from China, have raised landed costs for raw fisetin and finished extracts. Companies that rely on single-source procurement without hedging strategies or alternative supply routes are experiencing margin compression, forcing a reevaluation of global sourcing architectures.
Hesperidin Market
Key Growth Drivers
Technological Innovation in Extraction and Purification
The most consequential driver of fisetin market expansion is the maturation of extraction and purification technologies. Early commercial fisetin was often associated with moderate purity levels and inconsistent batch-to-batch performance, limiting its use to research and low-dose supplement formulations. Recent advances in controlled solvent systems, selective crystallization, and advanced chromatographic purification have enabled producers to consistently achieve 98 percent to 99 percent purity. These technological gains directly translate into higher active concentrations per gram, which reduces formulation volume, improves stability in complex matrices, and supports higher-value applications. The shift is not merely technical; it is commercial. Higher-purity fisetin commands premium pricing, supports longer shelf-life expectations, and opens the door to cosmeceutical and pharmaceutical-grade applications that were previously inaccessible. Producers investing in closed-loop extraction, in-process analytics, and validated purification pathways are positioning themselves to capture margin while simultaneously reducing waste and solvent recovery costs.
Regulatory Evolution and Safety Validation
Regulatory clarity is accelerating market confidence. The achievement of self-affirmed Generally Recognized as Safe (SA-GRAS) status for a leading branded fisetin ingredient marks a pivotal inflection point. This status, validated through systematic safety documentation and toxicological assessment, reduces regulatory friction for downstream dietary supplement and health product manufacturers seeking to incorporate fisetin into new formulations. Parallel developments reinforce this trajectory. An NDI notification filing for fisetin sourced from Cotinus coggygria was recorded in early 2025, signaling formal engagement with FDA processes for novel dietary ingredients. Toxicological data, including animal subchronic studies indicating a no-observed-adverse-effect level of 500 mg/kg/day, and human tolerability studies at 100 mg/day reporting no adverse events, provide a practical safety foundation that supports dose escalation in consumer and clinical applications. Regulatory progress does more than satisfy compliance; it lowers the barrier to commercial adoption, shortens formulation timelines, and enables marketing claims grounded in documented safety profiles.
Demand-Side Transformation Across Applications
Consumer and enterprise behavior is reshaping where fisetin creates value. In dietary supplements, demand is being driven by anti-aging, cellular longevity, and cognitive wellness narratives. Consumers are increasingly seeking ingredients with dual functional and health-span benefits, and fisetin's senolytic and neuroprotective research profile aligns with that expectation. Simultaneously, the cosmetics and personal care sector is exploring fisetin for its antioxidant and skin-resilience potential, although this application represents a smaller share of current revenue. The pharmaceutical and research segment remains focused on mechanistic studies, bioavailability optimization, and early-stage therapeutic exploration. Across these segments, a common theme emerges: buyers are moving from ingredient curiosity to evidence-based procurement. Formulators and brand owners are requesting batch-specific Certificates of Analysis, stability data, source transparency, and increasingly, clinical or tolerability documentation. This shift is compressing the market toward suppliers who can provide not only high-purity material but also verifiable quality systems and application support.
Supply Chain Reconfiguration and Cost Dynamics
Supply chain dynamics are evolving from cost-minimization to resilience-building. The market has seen a marked concentration of manufacturing capacity in China, where scale, extraction expertise, and certification infrastructure have matured rapidly. This concentration offers efficiency and price advantages but also introduces exposure to trade policy volatility, logistics disruption, and quality assurance complexity. In response, several manufacturers and distributors are diversifying source origins, qualifying multiple extraction sites, and strengthening documentation for traceability and compliance. At the same time, capacity expansion, with monthly production capabilities reaching multi-ton levels for select facilities, is beginning to address supply tightness for high-purity specifications. The net effect is a market where cost competitiveness is increasingly tied to process efficiency, yield optimization, and multi-source qualification rather than raw commodity pricing alone. Companies that structure their supply chains around redundancy, certification depth, and transparent sourcing are better positioned to protect margins while meeting the growing demand for auditable quality.
Worldwide Aescin Market
Competitive Landscape and Leading Strategies
The fisetin market is characterized by a concentrated yet evolving competitive field. Market concentration data indicates that a relatively small group of firms controls a substantial share of revenue, yet the landscape is not static. Leading players differentiate along purity capability, regulatory positioning, source material strategy, and application focus.
Strategic Positioning of Key Players
Companies with a demonstrated focus on high-purity fisetin are building defensible positions through process control and certification depth. Manufacturers specializing in 99 percent purity for nutraceutical and anti-aging supplement markets are competing on batch consistency, extraction yield, and downstream application support rather than price alone. Branded high-purity fisetin offerings that have achieved SA-GRAS status illustrate how regulatory differentiation can translate into commercial advantage. By combining purity at the 98–99 percent range with documented safety validation, such products reduce the compliance burden for customers and enable faster time-to-market for supplement and health product lines.
PW Consulting
Other manufacturers emphasize certification portfolios and sourcing flexibility. Factories operating with BRC, Organic, ISO9001, GMP, HACCP, and halal/kosher certifications address the procurement requirements of global buyers who need auditable quality systems. Some producers have expanded capacity significantly, with monthly output reaching several tons across multiple specifications, which improves supply reliability for bulk customers. This scale focus serves price-sensitive and volume-driven segments while maintaining access to a broad specification range. Meanwhile, suppliers focused on extract from Rhus succedanea or Cotinus coggygria differentiate by botanical origin, purity thresholds, and application orientation. Some position their material for cognitive health and nootropic formulations, while others serve food, nutraceutical, and pharmaceutical ingredient channels with purity up to 98 percent. Distributors and specialty chemical suppliers complement the landscape by providing API-grade fisetin, reference standards, and research-grade material, serving customers whose primary need is documentation, traceability, and analytical consistency rather than large-scale commercial volume.
Market Evolution Trends: Consolidation, Differentiation, and New Entry
Several structural trends are reshaping how the competitive field will evolve. First, consolidation pressure is rising among producers who lack scale or differentiated purity capability. As demand for 98 percent-plus fisetin grows and buyers demand stronger quality documentation, smaller extractors without advanced purification or certification infrastructure face margin erosion and potential acquisition or partnership scenarios. Second, differentiation is becoming the primary competitive lever. Brands that combine purity, regulatory status, and application-specific documentation are capturing premium positioning. This creates a bifurcated market: high-value, documentation-rich offerings on one side, and volume-oriented, specification-broad alternatives on the other. Third, new entrants are likely to emerge from two directions. Ingredient and formulation companies may enter by leveraging branded fisetin with regulatory credentials, while contract manufacturers may enter by offering toll-processing and purification services for buyers who prefer to own the botanical or extract source but outsource downstream purification. Regional diversification is also probable, as trade cost pressures incentivize buyers and suppliers to qualify non-China sourcing options or regional blending strategies to mitigate tariff exposure.
Forward Outlook: Three Trends Shaping the Next 3–5 Years
The data trajectory and current developments point to three interconnected trends.
- Purity and documentation become table stakes. The rapid uptake of 98 percent-plus fisetin, coupled with regulatory milestones such as SA-GRAS status and NDI filings, suggests that high-purity, well-documented material will increasingly be the baseline expectation rather than a premium differentiator. Suppliers that standardize high-purity production, batch quality analytics, and safety documentation will capture disproportionate share with formulators and brand owners.
- Application breadth will expand, but at uneven pace. Dietary supplements will likely remain the largest revenue anchor, supported by longevity and cognitive wellness demand. Cosmeceutical applications may grow as topical antioxidant and skin-resilience formulations incorporate fisetin, though this segment will require formulation stability data and cosmetic regulatory alignment. Pharmaceutical and research use will continue to advance in exploratory directions, but clinical translation will be stepwise and dependent on bioavailability improvements and trial outcomes.
- Supply chain resilience will determine margin stability. Trade policy, sourcing diversification, and capacity scaling will interact to shape cost structures. Companies with multi-source qualification, process efficiency, and documented quality systems will be better insulated from tariff-driven cost shocks and logistics volatility. Conversely, single-source dependency without hedging or qualification alternatives will remain a vulnerability.
These trends translate into clear commercial opportunities for players that act early. Suppliers can pursue premium positioning through purity-plus-documentation bundles and application support. Formulators and brands can accelerate product development by aligning with suppliers that reduce regulatory friction and provide batch consistency. Investors and corporate development teams can focus on assets with scalable purification capacity, certification depth, and diversified sourcing. At the same time, uncertainty warrants caution. Bioavailability limitations, the pace of clinical translation, and potential shifts in trade or regulatory policy could alter adoption speed. Demand concentration in a few application categories also means that market growth is sensitive to consumer sentiment and scientific narrative shifts.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient producers, the priority is to convert extraction and purification capability into a defensible commercial position. Investments in consistent high-purity output, in-process quality analytics, and certification breadth will differentiate offerings in a market where batch reliability and documentation increasingly drive purchasing decisions. Producers should also evaluate source diversification and regional supply qualification to reduce exposure to trade-related cost volatility, and consider branded positioning where regulatory status can be leveraged to shorten customer adoption cycles.
For investors and corporate strategy teams, the opportunity lies in identifying assets that combine scale, purity capability, and compliance readiness. Due diligence should emphasize production capacity stability, purity consistency across batches, documentation depth, and the ability to serve multiple application segments. Portfolio exposure should account for the uneven pace of application growth, with dietary supplements likely offering near-term scale and cosmeceutical or pharmaceutical pathways requiring longer development horizons and milestone-based risk assessment.
For procurement leaders and formulation teams, the focus should be on supplier qualification that prioritizes purity consistency, CoA transparency, stability data, and regulatory documentation over lowest unit price alone. Structuring supplier relationships around multi-source qualification, clear specification agreements, and application support can reduce formulation risk and accelerate product launches. Sourcing diversification should be evaluated not only for cost but also for resilience against trade and logistics disruptions.
Given the pace of regulatory developments, capacity expansions, and application evolution, decision makers benefit from continuous visibility into purity standardization progress, emerging regulatory milestones, competitive moves, and sourcing alternatives. Access to segmented, up-to-date market intelligence enables more precise timing for product development, supplier selection, and strategic investment. Additional detailed segmentation data and tailored commercial guidance remain available through the full PW Consulting report, which provides deeper breakdowns across purity specifications, application channels, regional dynamics, and company-level strategic benchmarks for those seeking to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Fisetin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com